Homeowners Policy 6/14/27
documentlook: clean
style: statement11 pages render unknown
Text layer
4394 words
4394 words on 11 pages, from pdftotext. This is what search finds in the file.
Show the text
                                                                                          PO Box 2280
                                                                                  Parsippany, NJ 07054

Fernhurst Mutual Insurance                                                              (866) 555-0151
                                                                               fernhurstmutual.example


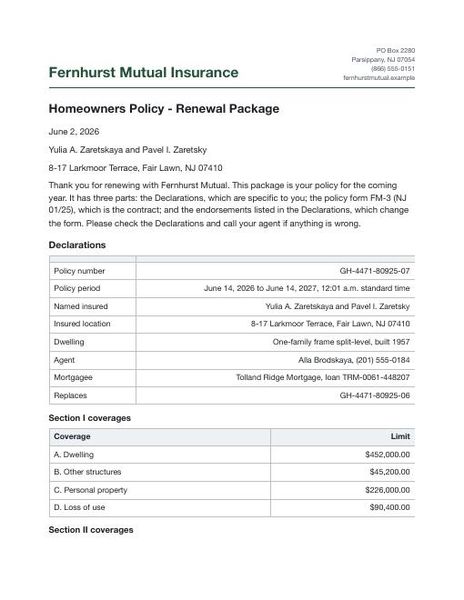
Homeowners Policy - Renewal Package
June 2, 2026

Yulia A. Zaretskaya and Pavel I. Zaretsky

8-17 Larkmoor Terrace, Fair Lawn, NJ 07410

Thank you for renewing with Fernhurst Mutual. This package is your policy for the coming
year. It has three parts: the Declarations, which are specific to you; the policy form FM-3 (NJ
01/25), which is the contract; and the endorsements listed in the Declarations, which change
the form. Please check the Declarations and call your agent if anything is wrong.

Declarations

 Policy number                                                                GH-4471-80925-07

 Policy period                           June 14, 2026 to June 14, 2027, 12:01 a.m. standard time

 Named insured                                           Yulia A. Zaretskaya and Pavel I. Zaretsky

 Insured location                                    8-17 Larkmoor Terrace, Fair Lawn, NJ 07410

 Dwelling                                                  One-family frame split-level, built 1957

 Agent                                                            Alla Brodskaya, (201) 555-0184

 Mortgagee                                       Tolland Ridge Mortgage, loan TRM-0061-448207

 Replaces                                                                     GH-4471-80925-06

Section I coverages

 Coverage                                                                                     Limit

 A. Dwelling                                                                          $452,000.00

 B. Other structures                                                                   $45,200.00

 C. Personal property                                                                 $226,000.00

 D. Loss of use                                                                        $90,400.00

Section II coverages
 Coverage                                                                               Limit

 E. Personal liability, each occurrence                                          $500,000.00

 F. Medical payments to others, each person                                        $5,000.00

Deductibles

 Peril                                                                            Deductible

 All perils except as shown below                                                  $1,500.00

 Hurricane (endorsement FM-HD)                                   2% of Coverage A, $9,040.00

Endorsements made part of this policy

 Endorsement                                                                            Limit

 FM-WB Water backup and sump overflow                                             $10,000.00

 FM-SP Scheduled personal property, 1 item                                         $1,450.00

 FM-HD Hurricane deductible                                                   see Deductibles

 FM-RS Roof surfacing, replaced September 2023                             surcharge removed

Premium

 Item                                                                                Amount

 Annual premium                                                                    $1,486.00

 Prior term premium                                                                $1,372.00

The premium is billed to the mortgagee. This policy does not cover flood. Flood insurance is
sold separately.

Homeowners Policy, Special Form FM-3 (NJ 01/25)

Agreement
We will provide the insurance described in this policy in return for the premium and your
compliance with all of its provisions. "You" and "your" mean the named insured shown in the
Declarations and that person's spouse if a resident of the same household. "We", "us" and
"our" mean Fernhurst Mutual Insurance.

Definitions
1. Bodily injury means bodily harm, sickness or disease, including required care, loss of
   services and death that results.
2. Business means a trade, profession or occupation engaged in on a full-time, part-time or
   occasional basis. Working for an employer from a home office is not, by itself, a business
   conducted at the insured location.
3. Insured means you and residents of your household who are your relatives, or other
   persons under the age of 21 in the care of any of them. A child of yours who is a full-time
   student and lived in your household before moving out to attend school remains an
   insured until age 24.
4. Insured location means the residence premises; any other premises you acquire during
   the policy period for use as a residence; a premises you rent for a short stay, such as a
   hotel room or a holiday rental; vacant land you own; and a cemetery plot or burial vault of
   an insured. A dwelling you own or co-own that is not shown in the Declarations, wherever
   it is, is not an insured location.
5. Occurrence means an accident, including continuous or repeated exposure to the same
   harmful conditions, that results during the policy period in bodily injury or property
   damage.
6. Property damage means physical injury to, destruction of, or loss of use of tangible
   property.
7. Residence premises means the one-family dwelling, other structures and grounds at the
   insured location shown in the Declarations.
8. Unoccupied means that no person is living in the dwelling for the time being although its
   contents remain. Vacant means that the dwelling does not contain enough furnishings for
   people to live in it.

Section I - Property

Coverage A - Dwelling
We cover the dwelling on the residence premises, including structures attached to it, and
materials and supplies on or next to the residence premises used to build, alter or repair it. We
do not cover land, including the land on which the dwelling stands.

Coverage B - Other structures
We cover structures on the residence premises set apart from the dwelling by clear space,
such as a detached garage, a shed, a fence or a deck that is not attached. The limit for
Coverage B is shown in the Declarations and is in addition to the Coverage A limit. We do not
cover a structure rented to someone who is not a tenant of the dwelling, or a structure from
which a business is conducted.

Coverage C - Personal property
We cover personal property owned or used by an insured while it is anywhere in the world. At
your request after a loss we will also cover property of a guest or a household employee while
it is in the residence premises.
Property usually kept at a residence of an insured other than the residence premises is
covered for up to 10% of the Coverage C limit, but not less than $1,000. This limitation does
not apply to property moved to a newly acquired principal residence for the first 30 days.

Special limits on certain property
The limits below do not increase the Coverage C limit. Each is the most we will pay in any one
loss for all property in that category, no matter how many items or insureds are involved.

1. $200 for money, bank notes, coins, stored-value cards and precious metals other than
   jewelry.
2. $1,500 for securities, deeds, passports, certificates, tickets, stamps and other personal
   records, whatever the medium. This limit includes the cost to research, replace or restore
   the information they held.
3. $1,500 for watercraft of all types, with their trailers, furnishings, equipment and motors.
4. $1,500 for trailers not used with watercraft.
5. $1,500 for loss by theft of jewelry, watches, furs, and precious and semiprecious stones.
6. $2,500 for loss by theft of silverware, goldware and pewterware.
7. $2,500 for property on the residence premises used mainly for business purposes, and
   $500 for such property away from the residence premises.
8. $1,500 for portable electronic devices, with their accessories, while away from the
   residence premises.
9. $5,000 for loss by theft of rugs, tapestries and wall hangings, with no more than $2,500 for
   any one article.

An article described in a Scheduled Personal Property endorsement is insured under that
endorsement for the amount shown for it, and the special limits above do not apply to it.
Articles of the same kind that are not described in the endorsement remain subject to the
special limits.

Property not covered under Coverage C
We do not cover: articles separately described and specifically insured in this or any other
insurance; animals, birds or fish; motor vehicles and their parts, other than vehicles not
required to be registered that are used to service the residence or to assist the handicapped;
aircraft; property of roomers and tenants not related to an insured; property in an apartment
regularly rented to others; and data, including records kept only in electronic form, beyond the
cost of blank media.

Coverage D - Loss of use
If a loss covered under Section I makes the part of the residence premises where you live unfit
to live in, we cover the necessary increase in your living expenses so that your household can
maintain its normal standard of living. Payment is for the shortest time required to repair the
damage or, if you move for good, to settle your household elsewhere, and in no event for
more than 24 months. If a civil authority forbids you to use the residence premises because of
direct damage to a neighbouring premises by a peril we insure against, we cover the same
expenses for up to two weeks.

Additional coverages
1. Debris removal. We pay your reasonable expense to remove debris of covered property
   after a covered loss. If the damage plus the debris removal is more than the limit for the
   property, an additional 5% of that limit is available.
2. Reasonable repairs. We pay the reasonable cost of necessary measures taken solely to
   protect covered property from further damage.
3. Trees, shrubs and plants. We cover trees, shrubs, plants and lawns on the residence
   premises for loss caused by fire, lightning, explosion, riot, aircraft, vehicles not owned or
   operated by a resident, vandalism or theft, up to 5% of the Coverage A limit and not more
   than $500 for any one tree, shrub or plant. Loss caused by wind, ice or the weight of snow
   is not covered.
4. Fire department service charge. Up to $500, with no deductible.
5. Credit card, fund transfer card, forgery and counterfeit money. Up to $1,000, with no
   deductible.
6. Loss assessment. Up to $1,000 for your share of an assessment charged by an
   association of property owners.
7. Refrigerated products. Up to $500 for food spoiled by an interruption of power or a
   mechanical failure of the appliance.
8. Lock replacement. Up to $500 to re-key or replace exterior locks when keys are lost or
   stolen, with no deductible.

Perils insured against
Coverages A and B. We insure against risk of direct physical loss to the property described
in Coverages A and B, unless the loss is excluded.

Coverage C. We insure for direct physical loss to the property described in Coverage C
caused by: fire or lightning; windstorm or hail; explosion; riot or civil commotion; aircraft;
vehicles; smoke; vandalism or malicious mischief; theft; falling objects; weight of ice, snow or
sleet; accidental discharge or overflow of water or steam from a plumbing, heating, air
conditioning or fire sprinkler system or from a household appliance; sudden and accidental
tearing apart, cracking, burning or bulging of such a system; freezing of such a system or
appliance; sudden and accidental damage from artificially generated electrical current; and
volcanic eruption.

Theft includes attempted theft and loss of property from a known place when it is likely that
the property has been stolen. Theft does not include loss caused by an insured; loss from a
dwelling under construction; property that is simply mislaid or lost; or theft from the part of
the residence premises rented by an insured to someone other than an insured.

Exclusions
We do not insure for loss caused directly or indirectly by any of the following. Such loss is
excluded whatever other cause or event contributes to it at the same time or in any sequence.

1. Ordinance or law. The enforcement of any ordinance or law regulating the construction,
   repair or demolition of a building, except as provided by endorsement.
2. Earth movement. Earthquake, landslide, mudflow, sinkhole, or earth sinking, rising or
   shifting. Direct loss by fire or explosion that follows is covered.
3. Water damage. Flood, surface water, waves, tidal water, overflow of a body of water, or
   spray from any of these, whether or not driven by wind; water that backs up through
   sewers or drains or overflows from a sump, except as provided by endorsement FM-WB;
   and water below the surface of the ground that presses on or seeps through a building,
   foundation, driveway or pool.
4. Power failure that takes place off the residence premises.
5. Neglect. Failure of an insured to use all reasonable means to save and preserve property
   at and after the time of a loss.
6. War, including undeclared war, civil war, insurrection, and seizure or use for a military
   purpose.
7. Nuclear hazard.
8. Intentional loss by or at the direction of an insured.
9. Governmental action. Destruction, confiscation or seizure of property by order of any
   government or public authority.

Under Coverages A and B we also do not insure for loss caused by: freezing of a plumbing or
heating system while the dwelling is vacant or unoccupied, unless you have used reasonable
care to maintain heat in the building or have shut off the water supply and drained the system;
wear and tear, deterioration, mold, wet or dry rot; smog, rust or corrosion; settling, cracking or
bulging of pavements, foundations, walls or ceilings; birds, vermin, rodents or insects; animals
owned or kept by an insured; continuous or repeated seepage or leakage of water over a
period of weeks, months or years; and vandalism, malicious mischief or breakage of glass if
the dwelling has been vacant for more than 60 consecutive days immediately before the loss.
A dwelling being constructed is not considered vacant.

Conditions - Section I
1. Insurable interest and limit of liability. Even if more than one person has an insurable
   interest in the property covered, we will not be liable in any one loss to an insured for more
   than the amount of that insured's interest at the time of loss, or for more than the
   applicable limit.
 2. Deductible. We pay only that part of the total of all loss payable under Section I that
    exceeds the deductible shown in the Declarations. If two deductibles could apply to one
    loss, only the larger applies.
 3. Your duties after loss. You must give prompt notice to us or to your agent; notify the
    police in case of loss by theft; notify the card issuer in case of loss under the credit card
    coverage; protect the property from further damage and keep a record of what you spend
    to do so; prepare an inventory of damaged personal property showing the quantity,
    description, age and amount of loss, with bills, receipts and related documents attached;
    show us the damaged property as often as we reasonably require; and send to us, within
    60 days after our request, your signed, sworn proof of loss.
 4. Loss settlement. Personal property, awnings, carpeting, household appliances and
    outdoor equipment are settled at actual cash value at the time of loss, but not more than
   the amount required to repair or replace. Buildings under Coverage A or B are settled at
   replacement cost without deduction for depreciation, provided that the amount of
   insurance on the damaged building is 80% or more of its full replacement cost
   immediately before the loss. Roof surfacing more than 15 years old at the time of loss is
    settled at actual cash value.
 5. Loss to a pair or set. We may either repair or replace any part to restore the pair or set to
    its value before the loss, or pay the difference between the actual cash value of the
    property before and after the loss.
 6. Appraisal. If you and we fail to agree on the amount of loss, either may demand an
    appraisal. Each party will choose a competent appraiser within 20 days after receiving a
    written request from the other. The two appraisers will choose an umpire. A decision
    agreed to by any two will set the amount of loss. Each party pays its own appraiser and
    shares the other costs equally.
 7. Other insurance. If a loss covered by this policy is also covered by other insurance, we
    will pay only the proportion of the loss that the limit that applies under this policy bears to
    the total amount of insurance covering the loss.
 8. Suit against us. No action can be brought against us unless there has been full
    compliance with the policy provisions and the action is started within two years after the
    date of loss.
 9. Loss payment. We will adjust all losses with you and pay you unless some other person is
    named in the policy or is legally entitled to receive payment. Loss will be payable 30 days
    after we receive your proof of loss and reach agreement with you, or there is an entry of a
    final judgment or the filing of an appraisal award.
10. Mortgage clause. If a mortgagee is named in this policy, any loss payable under
    Coverage A or B will be paid to the mortgagee and you, as interests appear. If we deny
    your claim, that denial will not apply to a valid claim of the mortgagee if the mortgagee
    notifies us of any change in ownership or occupancy of which it is aware, pays any
    premium due if you have neglected to pay it, and submits a signed, sworn statement of
    loss within 60 days after receiving notice from us of your failure to do so.
11. Abandonment of property. We need not accept any property abandoned by an insured.
12. Recovered property. If you or we recover any property for which we have made payment,
    the other will be notified. At your option the property will be returned to you, and the loss
    payment will be adjusted accordingly.

Section II - Liability

Coverage E - Personal liability
If a claim is made or a suit is brought against an insured for damages because of bodily injury
or property damage caused by an occurrence to which this coverage applies, we will pay up
to our limit of liability for the damages for which the insured is legally liable, and provide a
defense at our expense by counsel of our choice, even if the suit is groundless. Our duty to
settle or defend ends when the amount we pay for damages resulting from the occurrence
equals our limit of liability.

Coverage F - Medical payments to others
We will pay the necessary medical expenses incurred or medically ascertained within three
years from the date of an accident causing bodily injury to a person on the insured location
with the permission of an insured, or to a person off the insured location if the bodily injury is
caused by the activities of an insured or by an animal owned by or in the care of an insured.
This coverage does not apply to you or to regular residents of your household.

Exclusions - Section II
Coverages E and F do not apply to bodily injury or property damage:

 1. which is expected or intended by an insured;
 2. arising out of or in connection with a business engaged in by an insured;
 3. arising out of the rental or holding for rental of any part of any premises by an insured,
    other than the occasional rental of the residence premises for use only as a residence;
 4. arising out of the rendering of or failure to render professional services;
 5. arising out of a premises owned by an insured that is not an insured location;
 6. arising out of the ownership, maintenance, use, loading or unloading of motor vehicles,
    watercraft with more than 50 horsepower, or aircraft, other than model or hobby aircraft
    not designed to carry people;
 7. caused by the transmission of a communicable disease by an insured;
 8. arising out of the use, sale or possession of a controlled substance, other than the
    legitimate use of prescription drugs by a person following the orders of a licensed
    physician.
Coverage E also does not apply to liability assumed under an unwritten contract, to property
damage to property owned by an insured, or to bodily injury to you or to an insured.

Additional coverages - Section II
We cover the following in addition to the limits of liability: expenses we incur and costs taxed
against an insured in any suit we defend; premiums on bonds required in a suit we defend;
reasonable expenses incurred by an insured at our request, including actual loss of earnings
up to $250 per day, for assisting us in the investigation or defense of a claim; expenses for
first aid to others incurred by an insured at the time of an accident; and damage to property of
others caused by an insured, at replacement cost, up to $1,000 per occurrence.

Conditions - Section II
1. Limit of liability. Our total liability under Coverage E for all damages resulting from any
   one occurrence will not be more than the limit shown in the Declarations, regardless of the
   number of insureds, claims made or persons injured.
2. Duties after an occurrence. You must give written notice to us or to our agent as soon as
   is practical, setting out the identity of the policy and the insured, reasonably available
   information on the time, place and circumstances of the occurrence, and the names and
   addresses of any claimants and witnesses. You must promptly forward to us every notice,
   demand, summons or other process relating to the occurrence. An insured will not, except
   at the insured's own cost, voluntarily make payment, assume obligation or incur expense
   other than for first aid to others at the time of the bodily injury.
3. Payment of claim under Coverage F is not an admission of liability by an insured or by
   us.
4. Other insurance under Coverage E. This insurance is excess over other valid and
   collectible insurance, except insurance written specifically to cover as excess over the
   limits that apply in this policy.

Conditions that apply to Sections I and II
1. Policy period. This policy applies only to loss under Section I, or bodily injury or property
   damage under Section II, that occurs during the policy period.
2. Concealment or fraud. We do not provide coverage to an insured who, whether before or
   after a loss, has intentionally concealed or misrepresented any material fact or
   circumstance, engaged in fraudulent conduct, or made false statements relating to this
   insurance.
3. Changes in your household. Tell your agent within 60 days if a named insured's legal
   name changes; if a person joins or leaves the household; if you begin to rent out any part
   of the residence premises; if a business is started on the residence premises; or if the
   dwelling will be unoccupied for more than 60 consecutive days. Failure to tell us does not
   by itself void the policy, but it may limit what we pay.
 4. Liberalization. If we make a change that broadens coverage under this edition of the
    policy without additional premium, that change will automatically apply to your insurance
    as of the date we implement the change in your state.
 5. Waiver or change of policy provisions. A waiver or change of a provision of this policy
    must be in writing by us to be valid. Our request for an appraisal or examination will not
    waive any of our rights.
 6. Cancellation. You may cancel this policy at any time by returning it to us or by letting us
   know in writing of the date cancellation is to take effect. We may cancel by letting you
   know in writing at least 10 days before the date cancellation takes effect when you have
   not paid the premium, and at least 30 days before in any other case permitted by law.
   When this policy is cancelled, the premium for the period from the date of cancellation to
   the expiration date will be refunded pro rata.
 7. Nonrenewal. We may elect not to renew this policy. We may do so by delivering to you, or
    mailing to you at your mailing address shown in the Declarations, written notice at least 60
    days before the expiration date of this policy.
 8. Assignment. Assignment of this policy will not be valid unless we give our written
    consent.
 9. Subrogation. An insured may waive in writing before a loss all rights of recovery against
    any person. If not waived, we may require an assignment of rights of recovery for a loss to
    the extent that payment is made by us.
10. Death. If any person named in the Declarations or the spouse, if a resident of the same
   household, dies, we insure the legal representative of the deceased, but only with respect
   to the premises and property of the deceased covered under the policy at the time of
   death.

Endorsements

FM-WB - Water backup and sump overflow
We insure for direct physical loss to property covered under Section I caused by water, or
waterborne material, that backs up through sewers or drains, or that overflows or is
discharged from a sump, sump pump or related equipment, even if the overflow results from
the mechanical breakdown of the pump. The most we pay for all covered property in any one
loss under this endorsement is $10,000. A deductible of $1,000 applies to each loss under
this endorsement in place of the Section I deductible shown in the Declarations. This
endorsement does not cover the cost to repair or replace the pump itself, or loss caused by
flood, surface water or groundwater.

FM-SP - Scheduled personal property
 Item   Description                                                                  Amount of
                                                                                     insurance

 1      One pair of diamond stud earrings, 14k white gold, total weight 0.50           $1,450.00
        carat, appraisal of August 2019

We insure each scheduled article against risks of direct physical loss, including loss by
mysterious disappearance, anywhere in the world. No deductible applies. The amount shown
is the most we pay for the article. Jewelry acquired during the policy period is covered for up
to 30 days and for no more than 25% of the total amount scheduled, if you report it to us
within that time and pay the additional premium. This endorsement does not cover wear and
tear, gradual deterioration, inherent vice, or damage caused by a repair or restoration process.
Articles of jewelry that are not listed above are not insured by this endorsement.

FM-HD - Hurricane deductible
For loss caused by windstorm during a hurricane, the deductible is 2% of the Coverage A
limit shown in the Declarations, which for this policy period is $9,040.00, in place of any other
Section I deductible. A hurricane begins when a hurricane warning is issued for any part of
New Jersey and ends 24 hours after the last warning for any part of the state is ended. For
wind or hail losses at other times the deductible for all other perils applies.

FM-RS - Roof surfacing
We have recorded that the roof surfacing of the dwelling was fully replaced in September
2023. The surcharge for roof age has been removed for this policy period. Condition 4 of
Section I continues to apply to roof surfacing by its age at the time of a loss.

How to report a claim
Call (866) 555-0151 at any hour, or your agent during business hours. Have the policy number,
the date and cause of the loss and a description of the damage. Do not throw away damaged
property before our adjuster has seen it unless it is a hazard. Keep receipts for emergency
repairs and for extra living expenses.

Signed for Fernhurst Mutual Insurance by its Secretary and its President at Parsippany, New
Jersey.
Comments
0
Comments are added in the local viewer; this copy is read-only.
Values from records
5render unknown
The record values this file is made from: the ones its text names with {{record.field}}, and the fields its template reads. A value here is in the file's source; whether it is readable depends on the look.
| Value | Now |
|---|---|
| home-policy-2026.policy_number | GH-4471-80925-07 |
| home-policy-2026.expiration | 2027-06-14 |
| mortgage-tolland.account_number | TRM-0061-448207 |
| home-policy-2025.policy_number | GH-4471-80925-06 |
| home-policy-2025.annual_premium | 1372 |
The values at render time were not recorded: the file was rendered before files/rendered.json existed. Rendering it again records them.