Dataset viewer

DM-HO-2087341-07

personas/retired-couple/files/finance/home-policy-2026.pdf
documentlook: clean style: statement8 pages render unknown

Text layer

3044 words

3044 words on 8 pages, from pdftotext. This is what search finds in the file.

Show the text
                                                                                            PO Box 2210
                                                                                      Viroqua, WI 54665

Driftless Mutual Insurance Company                                                        (855) 555-0112
                                                                               driftlessmutual.example


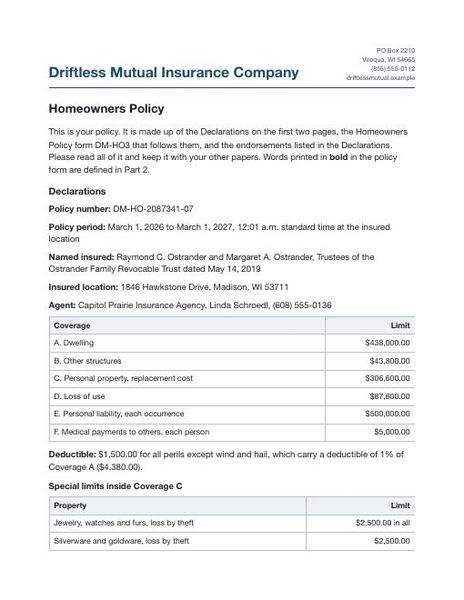
Homeowners Policy
This is your policy. It is made up of the Declarations on the first two pages, the Homeowners
Policy form DM-HO3 that follows them, and the endorsements listed in the Declarations.
Please read all of it and keep it with your other papers. Words printed in bold in the policy
form are defined in Part 2.

Declarations
Policy number: DM-HO-2087341-07

Policy period: March 1, 2026 to March 1, 2027, 12:01 a.m. standard time at the insured
location

Named insured: Raymond C. Ostrander and Margaret A. Ostrander, Trustees of the
Ostrander Family Revocable Trust dated May 14, 2019

Insured location: 1846 Hawkstone Drive, Madison, WI 53711

Agent: Capitol Prairie Insurance Agency, Linda Schroedl, (608) 555-0136

 Coverage                                                                                      Limit

 A. Dwelling                                                                         $438,000.00

 B. Other structures                                                                   $43,800.00

 C. Personal property, replacement cost                                              $306,600.00

 D. Loss of use                                                                        $87,600.00

 E. Personal liability, each occurrence                                              $500,000.00

 F. Medical payments to others, each person                                              $5,000.00

Deductible: $1,500.00 for all perils except wind and hail, which carry a deductible of 1% of
Coverage A ($4,380.00).

Special limits inside Coverage C

 Property                                                                                      Limit

 Jewelry, watches and furs, loss by theft                                         $2,500.00 in all

 Silverware and goldware, loss by theft                                                  $2,500.00
 Property                                                                                 Limit

 Firearms, loss by theft                                                             $2,500.00

 Money and bank notes                                                                  $200.00

 Watercraft, with trailers and motors                                                $1,500.00

Articles insured under a separate scheduled policy are not covered here.

Forms and endorsements that are part of this policy

 Form                  Title                                                      Limit or note

 DM-HO3 (01/24)        Homeowners Policy, special form

 DM-WB (01/24)         Water backup and sump overflow          $25,000.00, deductible $1,000.00

 DM-SL (06/22)         Underground service lines                 $10,000.00, deductible $500.00

 DM-RS (01/24)         Roof surfaces, replacement cost                roof replaced August 2021

 DM-TR (03/19)         Residence held in trust

 DM-WI (01/25)         Wisconsin changes

This policy does not cover flood or earthquake.

Premium

 Item                                                                                  Amount

 Annual premium                                                                      $1,862.00

 Claim-free, protective device and multi-policy discounts                             included

 Paid in full                                                                February 23, 2026


Homeowners Policy, form DM-HO3 (01/24)

Part 1. Our agreement with you
We will give you the insurance described in this policy in return for the premium and for your
keeping to its terms. The Declarations show which coverages you have bought and their
limits. A coverage with no limit shown in the Declarations is not in force.

Part 2. What some words mean
1. You and your mean the named insured in the Declarations and, if living in the same
   household, that person's spouse. We, us and our mean Driftless Mutual Insurance
   Company.
2. Insured means you; your relatives who live in your household; and anyone under 21 in the
   care of one of those people.
3. Residence premises means the one-family dwelling, the other structures and the grounds
   at the insured location in the Declarations.
4. Occurrence means an accident, including continued or repeated exposure to the same
   harmful conditions, that results in bodily injury or property damage during the policy
   period.
5. Actual cash value means the cost to repair or replace with material of like kind and
   quality, less an allowance for age and wear.
6. Unoccupied means that no insured has stayed overnight in the dwelling, although the
   furniture and belongings are still in it. Vacant means that the dwelling holds no furnishings
   to live with. A dwelling being built or remodeled is not vacant.
7. Business means a trade, profession or occupation carried on for pay. It does not mean
   volunteer work, or the occasional sale of handwork or baked goods that brings in less than
   $3,000 in a year.
8. Bodily injury means bodily harm, sickness or disease, and the care, loss of services and
   death that result from it. Property damage means physical injury to tangible property, or
   its destruction, and the loss of its use.
9. Residence employee means a person an insured pays to work in or about the residence
   premises, such as someone who cleans, mows, shovels or gives care in the home.

Part 3. The property we cover
Coverage A, dwelling. We cover the dwelling on the residence premises, structures attached
to it, and materials on the premises for building or repairing it.

Coverage B, other structures. We cover structures on the residence premises that are set
apart from the dwelling by clear space: a detached garage, a shed, a fence. We do not cover
a structure rented to someone who does not live in the dwelling, or one used for business.

Coverage C, personal property. We cover personal property that an insured owns or uses,
anywhere in the world. Property that is usually kept at another residence of yours is covered
for up to 10% of the Coverage C limit. The special limits in the Declarations are the most we
pay for those kinds of property; they do not add to the Coverage C limit. We do not cover
animals, motor vehicles and their parts, aircraft, property of roomers, or articles separately
described and insured by any other insurance.

Property we do not cover under Coverage C:

   animals, birds and fish;
   motor vehicles, their equipment and parts, other than a lawn tractor, a snow blower or a
   mobility chair that is not licensed for the road;
   aircraft and their parts, other than model aircraft;
   property of a roomer or tenant who is not related to you;
   business records and data, beyond the cost of blank media;
   property in an apartment that you regularly rent to others.

Coverage D, loss of use. If a loss we cover makes the dwelling unfit to live in, we pay the
added cost of living elsewhere for the shortest time needed to repair the dwelling or for you to
settle elsewhere, and for no longer than 24 months.

Other things we pay for. These are in addition to the limits above unless we say otherwise.

   Removing the debris of covered property, and up to $1,000.00 to remove a tree that has
   fallen on a covered structure or blocks the driveway.
   The reasonable cost of repairs you make to protect property from more damage after a
   covered loss.
   Trees, shrubs and lawns, for loss by fire, lightning, explosion, vehicles not driven by a
   resident, vandalism or theft: up to $500.00 for one plant and 5% of Coverage A in all.
   A fire department charge, up to $1,000.00. No deductible applies.
   The forged or unauthorized use of a credit card or check of yours, up to $1,000.00. No
   deductible applies.
   The added cost of meeting a building code when a covered loss is repaired, up to 10% of
   Coverage A.

Part 4. The causes of loss we cover
For the dwelling and other structures we cover direct physical loss from any cause, except
the causes in Part 5 and except: wear and tear; rust, rot and mold; settling and cracking of
walls, floors and foundations; birds, rodents and insects; the seepage of water over weeks or
months; and freezing, which we cover only as condition 6.4 allows.

For personal property we cover direct physical loss caused by fire or lightning; windstorm or
hail; explosion; riot; aircraft; vehicles; smoke; vandalism; theft; falling objects; the weight of
ice, snow or sleet; the sudden escape of water or steam from plumbing, heating or an
appliance; the sudden tearing or bursting of a heating system or water heater; freezing of
plumbing or an appliance, as condition 6.4 allows; and sudden damage from an artificial
electric current.

Part 5. What we do not cover
We do not pay for loss caused by any of these, whatever else contributed to it.

1. Water from outside. Flood, surface water, waves, the overflow of a body of water, and
   water below the ground that presses on or seeps through a foundation, floor or wall. Water
   that backs up through a sewer or drain is covered only by endorsement DM-WB and only
   up to its limit.
2. Earth movement. Earthquake, landslide, sinkhole and the sinking or shifting of the
   ground.
3. Law. The enforcement of a law about building or tearing down, beyond what Part 3 allows.
4. Failure of power that begins away from the residence premises.
5. Neglect. The failure of an insured to use all reasonable means to save property at and
   after a loss.
6. War and nuclear hazard.
7. Loss on purpose. A loss that an insured causes or arranges with the intent to cause a
   loss.

Part 6. Conditions for property claims
6.1 What you must do after a loss. Tell us or your agent promptly, and the police if the loss
is a theft. Protect the property from more damage and keep the receipts for what that costs.
Make a list of the damaged and stolen property showing quantity, description, age and value,
with the bills, receipts and photographs you have. Show us the property as often as we
reasonably ask. Send us a signed proof of loss within 60 days of our asking for one.

6.2 How we settle. The dwelling and other structures are settled at the cost to repair or
replace, without an allowance for age, if at the time of loss Coverage A is at least 80% of the
cost to rebuild. Until the repair is done we pay actual cash value. Personal property is settled
at replacement cost as the Declarations show. We pay within 30 days after we reach
agreement with you.

6.3 Deductible. We pay only the part of a loss that is over the deductible in the Declarations.
One deductible applies to one occurrence.

6.4 When the home is left unoccupied in cold weather. If the dwelling has been
unoccupied for more than 14 days in a row at any time from November 1 through March 31,
we do not pay for loss caused by the freezing of plumbing, heating, air conditioning or a
household appliance, or by water that escapes from one of them after it has frozen, unless for
the whole of the time away either (a) the water was shut off where it enters the dwelling and
the pipes and appliances were drained, or (b) the heat was kept on with the thermostat set no
lower than 55 degrees Fahrenheit and an adult you had asked to do so went inside the
dwelling at least once every 4 days to see that the heat was working. Collecting the mail or
looking at the house from outside is not enough. We may ask who made the visits and on
which days.

6.5 When the home is vacant. If the dwelling has been vacant for more than 60 days in a row
before a loss, we do not pay for vandalism, theft, or the breaking of glass.

6.6 If we disagree on the amount. Either of us may ask in writing for an appraisal. Each
chooses an appraiser within 20 days, and the two choose an umpire. Agreement by any two
sets the amount of the loss. Each side pays its own appraiser and half of the umpire.
6.7 Suit against us. No one may bring an action against us unless the terms of this policy
have been kept and the action is started within one year after the loss.

6.8 Mortgage. No mortgage holder is named in the Declarations. If one is named later, a loss
on the dwelling is paid to the holder and to you as your interests appear.

6.9 Other insurance. If other insurance covers the same loss, we pay only our share. Articles
that are scheduled on another policy are covered by that policy and not by this one.

6.10 Pairs and sets. If one of a pair or part of a set is lost or damaged, we may repair or
replace the part so that the pair or set is as it was, or pay the difference between the actual
cash value of the property before the loss and after it.

6.11 Glass. Broken glass is replaced with safety glass where the building code requires it.

6.12 Property found again. If property we have paid for is recovered, tell us. You may keep
the payment and let us have the property, or take the property back and return what we paid
for it.

6.13 Abandonment. We need not accept property that you leave to us.

Part 7. Liability to others
Coverage E, personal liability. If a claim is made or a suit is brought against an insured for
bodily injury or property damage caused by an occurrence, we pay up to the Coverage E limit
for the damages the insured is legally bound to pay, and we provide a defense with a lawyer
we choose. Our duty to defend ends when the limit has been paid out.

Coverage F, medical payments to others. We pay the necessary medical expenses, within
three years of an accident, of a person who is hurt on the residence premises with an
insured's permission, or hurt elsewhere by what an insured or an insured's animal does. This
does not apply to you or to people who live in your household.

We do not cover under Part 7: injury or damage that an insured intends; anything arising out
of a business; the ownership or use of a motor vehicle, an aircraft, or a boat with a motor of
more than 25 horsepower; liability you take on under a contract, except a written lease;
damage to property an insured owns; or the passing on of a communicable disease.

We also pay the costs of a suit we defend; interest on a judgment; the cost of first aid to
others at the time of an accident; and up to $1,000.00 for damage an insured does to
someone else's property, whoever is at fault.

If there is a claim under Part 7, the insured must give us written notice as soon as practical,
with the time, place and names of those hurt and of witnesses; send us at once every letter,
summons or other paper that arrives; help us to settle or defend; and not make any payment
or promise, except for first aid, without our consent. Bankruptcy of an insured does not relieve
us of our duties. The Coverage E limit is the most we pay for one occurrence however many
insureds, claims or injured people there are.

Part 8. Conditions for the whole policy
8.1 Concealment or fraud. The whole policy is void for an insured who, before or after a loss,
has on purpose hidden or misstated a fact that matters.

8.2 Changes. Only a written endorsement from us changes this policy. If we broaden a form
at no added premium during the policy period, you have the broader cover from the day it
takes effect in Wisconsin.

8.3 Cancelling. You may cancel at any time by writing to us. We may cancel for unpaid
premium with 10 days' notice. After the policy has been in force 60 days we may otherwise
cancel only for a material misstatement or a large change in the risk, with 30 days' notice.

8.4 Not renewing. If we decide not to renew, we will mail you notice at least 60 days before
the end of the policy period.

8.5 Your death. If you die, we insure your legal representative for the premises and property
covered at the time of death, and the members of your household while they go on living
there.

8.6 Mutual company. You are a member of Driftless Mutual Insurance Company while this
policy is in force and may vote at the annual meeting, held on the second Tuesday of March at
our office in Viroqua. This policy is not assessable.

Endorsements
DM-WB, water backup and sump overflow. We pay up to $25,000.00 for direct loss caused
by water that backs up through a sewer or drain, or that overflows from a sump even if the
pump has failed. The deductible for this cover is $1,000.00. It does not cover flood or surface
water.

DM-SL, underground service lines. We pay up to $10,000.00 to repair or replace a water,
sewer, gas or electric line that you own and that fails underground on the residence premises,
with the digging and the making good of the lawn and walks. The deductible for this cover is
$500.00.

DM-RS, roof surfaces. Loss to the roof surface by wind or hail is settled at replacement cost
with no allowance for age, in place of any schedule that would otherwise apply.

DM-TR, residence held in trust. The named insured is the trustees of the trust in the
Declarations. Raymond C. Ostrander and Margaret A. Ostrander, who live in the dwelling, are
insureds as though they were named in their own right. Tell us within 60 days if the trustees
change or the trust comes to an end.
DM-WI, Wisconsin changes. Where a term of this policy is in conflict with the statutes of
Wisconsin, the statute applies.

Countersigned at Viroqua, Wisconsin, February 9, 2026.   Dale R. Hegge, Secretary
Notices that come with your policy
Your renewal. Coverage A was raised by 4% at this renewal, from $421,000.00 to
$438,000.00, to keep pace with the cost of building, and Coverages B, C and D rose in step.
At your request the deductible for perils other than wind and hail was changed from $1,000.00
to $1,500.00. The water backup limit was raised from $10,000.00 to $25,000.00 and the
service line endorsement was added.

Discounts on this policy. No claims in the past ten years; a central-station burglar and fire
alarm; a roof less than ten years old; and an automobile policy with us.

To report a claim call (855) 555-0112 at any hour, or your agent during office hours. Have the
policy number, the date of the loss and a telephone number where you can be reached. Do
not throw away damaged property until our adjuster has seen it or has told you that you may.

If you are away in winter, read condition 6.4 before you leave. Members who spend part of
the winter elsewhere are asked to leave with a neighbor or relative the name of their agent and
of a plumber and a heating contractor.

If you have a complaint that we have not been able to settle, you may write to the Wisconsin
Office of the Commissioner of Insurance. We will send you the address on request.


Comments

0

Comments are added in the local viewer; this copy is read-only.
Values from records

5render unknown

The record values this file is made from: the ones its text names with {{record.field}}, and the fields its template reads. A value here is in the file's source; whether it is readable depends on the look.

ValueNow
home-policy-2026.policy_number DM-HO-2087341-07
home-policy-2026.expiration 2027-03-01
home-policy-2026.insured_value 438000
home-policy-2026.deductible 1500
home-policy-2026.annual_premium 1862

The values at render time were not recorded: the file was rendered before files/rendered.json existed. Rendering it again records them.

Planted

near_duplicate Each current policy sits next to last year's. Peg has an old and a new passport. Two diamond solitaire rings, hers and her mother's. Old and new doses of the same drug. Two jewelry appraisals eight years apart, whose names no longer say which is current. Two years of the accountant's summary. The 2019 wills and the 2003 ones are both still in the grey box, per two notes. Not every expired policy is labelled as such any more; the dates say it.

two_of_a_kind Two houses, each with its own policy, deed, tax bills and contents. Each policy has its own rule about freezing while the place is empty, with different numbers. Three cars, one of them sold. Two dogs, one of them dead.

only_in_file The facts kept in one file and nowhere else. The long-term care daily benefit ($272.27) is only on the schedule. The life policy's cash value is only on its statement. The cabin's wind deductible ($7,700) and its theft and tree limits are only on its declarations. The house policy's jewelry sublimit, water backup limit and the rule about leaving the house empty in winter (condition 6.4, on page 5 of 8) are only in the policy. Ray's LDL of 68 is only on the lab sheet. Adjusted gross income for 2025 ($116,640) and for 2024 ($109,870) is only in each year's summary. The truck's title number is only on the title (that there is no lien also follows from the purchase receipt's "no loan"). The value of Peg's IRA is only on its statement. The septic system's design and the county's three-year pumping rule are only on the permit.

attachments.yaml
record: home-policy-2026
template: document
style: statement
org:
  name: Driftless Mutual Insurance Company
  lines:
  - PO Box 2210
  - Viroqua, WI 54665
  phone: '8555550112'
  web: driftlessmutual.example
  color: '#1e4d6b'
title: Homeowners Policy
body: "This is your policy. It is made up of the Declarations on the first two pages, the Homeowners Policy\
  \ form\nDM-HO3 that follows them, and the endorsements listed in the Declarations. Please read all of\
  \ it and keep\nit with your other papers. Words printed in **bold** in the policy form are defined in\
  \ Part 2.\n\n## Declarations\n\n**Policy number:** {{home-policy-2026.policy_number}}\n\n**Policy period:**\
  \ March 1, 2026 to {{home-policy-2026.expiration}}, 12:01 a.m. standard time at the insured location\n\
  \n**Named insured:** Raymond C. Ostrander and Margaret A. Ostrander, Trustees of the Ostrander Family\
  \ Revocable Trust dated May 14, 2019\n\n**Insured location:** 1846 Hawkstone Drive, Madison, WI 53711\n\
  \n**Agent:** Capitol Prairie Insurance Agency, Linda Schroedl, (608) 555-0136\n\n| Coverage | Limit\
  \ |\n|---|---|\n| A. Dwelling | {{home-policy-2026.insured_value|money}} |\n| B. Other structures |\
  \ $43,800.00 |\n| C. Personal property, replacement cost | $306,600.00 |\n| D. Loss of use | $87,600.00\
  \ |\n| E. Personal liability, each occurrence | $500,000.00 |\n| F. Medical payments to others, each\
  \ person | $5,000.00 |\n\n**Deductible:** {{home-policy-2026.deductible|money}} for all perils except\
  \ wind and hail, which carry a deductible of 1% of Coverage A ($4,380.00).\n\n### Special limits inside\
  \ Coverage C\n\n| Property | Limit |\n|---|---|\n| Jewelry, watches and furs, loss by theft | $2,500.00\
  \ in all |\n| Silverware and goldware, loss by theft | $2,500.00 |\n| Firearms, loss by theft | $2,500.00\
  \ |\n| Money and bank notes | $200.00 |\n| Watercraft, with trailers and motors | $1,500.00 |\n\nArticles\
  \ insured under a separate scheduled policy are not covered here.\n\n### Forms and endorsements that\
  \ are part of this policy\n\n| Form | Title | Limit or note |\n|---|---|---|\n| DM-HO3 (01/24) | Homeowners\
  \ Policy, special form | |\n| DM-WB (01/24) | Water backup and sump overflow | $25,000.00, deductible\
  \ $1,000.00 |\n| DM-SL (06/22) | Underground service lines | $10,000.00, deductible $500.00 |\n| DM-RS\
  \ (01/24) | Roof surfaces, replacement cost | roof replaced August 2021 |\n| DM-TR (03/19) | Residence\
  \ held in trust | |\n| DM-WI (01/25) | Wisconsin changes | |\n\nThis policy does not cover flood or\
  \ earthquake.\n\n### Premium\n\n| Item | Amount |\n|---|---|\n| Annual premium | {{home-policy-2026.annual_premium|money}}\
  \ |\n| Claim-free, protective device and multi-policy discounts | included |\n| Paid in full | February\
  \ 23, 2026 |\n\n## Homeowners Policy, form DM-HO3 (01/24)\n\n### Part 1. Our agreement with you\n\n\
  We will give you the insurance described in this policy in return for the premium and for your keeping\
  \ to\nits terms. The Declarations show which coverages you have bought and their limits. A coverage\
  \ with no limit\nshown in the Declarations is not in force.\n\n### Part 2. What some words mean\n\n\
  1. **You** and **your** mean the named insured in the Declarations and, if living in the same household,\n\
  \   that person's spouse. **We**, **us** and **our** mean Driftless Mutual Insurance Company.\n2. **Insured**\
  \ means you; your relatives who live in your household; and anyone under 21 in the care of\n   one of\
  \ those people.\n3. **Residence premises** means the one-family dwelling, the other structures and the\
  \ grounds at the\n   insured location in the Declarations.\n4. **Occurrence** means an accident, including\
  \ continued or repeated exposure to the same harmful\n   conditions, that results in bodily injury or\
  \ property damage during the policy period.\n5. **Actual cash value** means the cost to repair or replace\
  \ with material of like kind and quality, less\n   an allowance for age and wear.\n6. **Unoccupied**\
  \ means that no insured has stayed overnight in the dwelling, although the furniture and\n   belongings\
  \ are still in it. **Vacant** means that the dwelling holds no furnishings to live with. A\n   dwelling\
  \ being built or remodeled is not vacant.\n7. **Business** means a trade, profession or occupation carried\
  \ on for pay. It does not mean volunteer\n   work, or the occasional sale of handwork or baked goods\
  \ that brings in less than $3,000 in a year.\n8. **Bodily injury** means bodily harm, sickness or disease,\
  \ and the care, loss of services and death\n   that result from it. **Property damage** means physical\
  \ injury to tangible property, or its\n   destruction, and the loss of its use.\n9. **Residence employee**\
  \ means a person an insured pays to work in or about the residence premises,\n   such as someone who\
  \ cleans, mows, shovels or gives care in the home.\n\n### Part 3. The property we cover\n\n**Coverage\
  \ A, dwelling.** We cover the dwelling on the residence premises, structures attached to it, and\nmaterials\
  \ on the premises for building or repairing it.\n\n**Coverage B, other structures.** We cover structures\
  \ on the residence premises that are set apart from the\ndwelling by clear space: a detached garage,\
  \ a shed, a fence. We do not cover a structure rented to someone\nwho does not live in the dwelling,\
  \ or one used for business.\n\n**Coverage C, personal property.** We cover personal property that an\
  \ insured owns or uses, anywhere in the\nworld. Property that is usually kept at another residence of\
  \ yours is covered for up to 10% of the Coverage C\nlimit. The special limits in the Declarations are\
  \ the most we pay for those kinds of property; they do not\nadd to the Coverage C limit. We do not cover\
  \ animals, motor vehicles and their parts, aircraft, property of\nroomers, or articles separately described\
  \ and insured by any other insurance.\n\n**Property we do not cover** under Coverage C:\n\n- animals,\
  \ birds and fish;\n- motor vehicles, their equipment and parts, other than a lawn tractor, a snow blower\
  \ or a mobility\n  chair that is not licensed for the road;\n- aircraft and their parts, other than\
  \ model aircraft;\n- property of a roomer or tenant who is not related to you;\n- business records and\
  \ data, beyond the cost of blank media;\n- property in an apartment that you regularly rent to others.\n\
  \n**Coverage D, loss of use.** If a loss we cover makes the dwelling unfit to live in, we pay the added\
  \ cost\nof living elsewhere for the shortest time needed to repair the dwelling or for you to settle\
  \ elsewhere, and\nfor no longer than 24 months.\n\n**Other things we pay for.** These are in addition\
  \ to the limits above unless we say otherwise.\n\n- Removing the debris of covered property, and up\
  \ to $1,000.00 to remove a tree that has fallen on a\n  covered structure or blocks the driveway.\n\
  - The reasonable cost of repairs you make to protect property from more damage after a covered loss.\n\
  - Trees, shrubs and lawns, for loss by fire, lightning, explosion, vehicles not driven by a resident,\n\
  \  vandalism or theft: up to $500.00 for one plant and 5% of Coverage A in all.\n- A fire department\
  \ charge, up to $1,000.00. No deductible applies.\n- The forged or unauthorized use of a credit card\
  \ or check of yours, up to $1,000.00. No deductible applies.\n- The added cost of meeting a building\
  \ code when a covered loss is repaired, up to 10% of Coverage A.\n\n### Part 4. The causes of loss we\
  \ cover\n\n**For the dwelling and other structures** we cover direct physical loss from any cause, except\
  \ the causes\nin Part 5 and except: wear and tear; rust, rot and mold; settling and cracking of walls,\
  \ floors and\nfoundations; birds, rodents and insects; the seepage of water over weeks or months; and\
  \ freezing, which we\ncover only as condition 6.4 allows.\n\n**For personal property** we cover direct\
  \ physical loss caused by fire or lightning; windstorm or hail;\nexplosion; riot; aircraft; vehicles;\
  \ smoke; vandalism; theft; falling objects; the weight of ice, snow or\nsleet; the sudden escape of\
  \ water or steam from plumbing, heating or an appliance; the sudden tearing or\nbursting of a heating\
  \ system or water heater; freezing of plumbing or an appliance, as condition 6.4\nallows; and sudden\
  \ damage from an artificial electric current.\n\n### Part 5. What we do not cover\n\nWe do not pay for\
  \ loss caused by any of these, whatever else contributed to it.\n\n1. **Water from outside.** Flood,\
  \ surface water, waves, the overflow of a body of water, and water below\n   the ground that presses\
  \ on or seeps through a foundation, floor or wall. Water that backs up through a\n   sewer or drain\
  \ is covered only by endorsement DM-WB and only up to its limit.\n2. **Earth movement.** Earthquake,\
  \ landslide, sinkhole and the sinking or shifting of the ground.\n3. **Law.** The enforcement of a law\
  \ about building or tearing down, beyond what Part 3 allows.\n4. **Failure of power** that begins away\
  \ from the residence premises.\n5. **Neglect.** The failure of an insured to use all reasonable means\
  \ to save property at and after a loss.\n6. **War and nuclear hazard.**\n7. **Loss on purpose.** A loss\
  \ that an insured causes or arranges with the intent to cause a loss.\n\n### Part 6. Conditions for\
  \ property claims\n\n**6.1 What you must do after a loss.** Tell us or your agent promptly, and the\
  \ police if the loss is a\ntheft. Protect the property from more damage and keep the receipts for what\
  \ that costs. Make a list of the\ndamaged and stolen property showing quantity, description, age and\
  \ value, with the bills, receipts and\nphotographs you have. Show us the property as often as we reasonably\
  \ ask. Send us a signed proof of loss\nwithin 60 days of our asking for one.\n\n**6.2 How we settle.**\
  \ The dwelling and other structures are settled at the cost to repair or replace,\nwithout an allowance\
  \ for age, if at the time of loss Coverage A is at least 80% of the cost to rebuild.\nUntil the repair\
  \ is done we pay actual cash value. Personal property is settled at replacement cost as the\nDeclarations\
  \ show. We pay within 30 days after we reach agreement with you.\n\n**6.3 Deductible.** We pay only\
  \ the part of a loss that is over the deductible in the Declarations. One\ndeductible applies to one\
  \ occurrence.\n\n**6.4 When the home is left unoccupied in cold weather.** If the dwelling has been\
  \ unoccupied for more\nthan 14 days in a row at any time from November 1 through March 31, we do not\
  \ pay for loss caused by the\nfreezing of plumbing, heating, air conditioning or a household appliance,\
  \ or by water that escapes from one\nof them after it has frozen, unless for the whole of the time away\
  \ either (a) the water was shut off where\nit enters the dwelling and the pipes and appliances were\
  \ drained, or (b) the heat was kept on with the\nthermostat set no lower than 55 degrees Fahrenheit\
  \ and an adult you had asked to do so went inside the\ndwelling at least once every 4 days to see that\
  \ the heat was working. Collecting the mail or looking at\nthe house from outside is not enough. We\
  \ may ask who made the visits and on which days.\n\n**6.5 When the home is vacant.** If the dwelling\
  \ has been vacant for more than 60 days in a row before a\nloss, we do not pay for vandalism, theft,\
  \ or the breaking of glass.\n\n**6.6 If we disagree on the amount.** Either of us may ask in writing\
  \ for an appraisal. Each chooses an\nappraiser within 20 days, and the two choose an umpire. Agreement\
  \ by any two sets the amount of the loss.\nEach side pays its own appraiser and half of the umpire.\n\
  \n**6.7 Suit against us.** No one may bring an action against us unless the terms of this policy have\
  \ been\nkept and the action is started within one year after the loss.\n\n**6.8 Mortgage.** No mortgage\
  \ holder is named in the Declarations. If one is named later, a loss on the\ndwelling is paid to the\
  \ holder and to you as your interests appear.\n\n**6.9 Other insurance.** If other insurance covers\
  \ the same loss, we pay only our share. Articles that are\nscheduled on another policy are covered by\
  \ that policy and not by this one.\n\n**6.10 Pairs and sets.** If one of a pair or part of a set is\
  \ lost or damaged, we may repair or replace\nthe part so that the pair or set is as it was, or pay the\
  \ difference between the actual cash value of the\nproperty before the loss and after it.\n\n**6.11\
  \ Glass.** Broken glass is replaced with safety glass where the building code requires it.\n\n**6.12\
  \ Property found again.** If property we have paid for is recovered, tell us. You may keep the\npayment\
  \ and let us have the property, or take the property back and return what we paid for it.\n\n**6.13\
  \ Abandonment.** We need not accept property that you leave to us.\n\n### Part 7. Liability to others\n\
  \n**Coverage E, personal liability.** If a claim is made or a suit is brought against an insured for\
  \ bodily\ninjury or property damage caused by an occurrence, we pay up to the Coverage E limit for the\
  \ damages the\ninsured is legally bound to pay, and we provide a defense with a lawyer we choose. Our\
  \ duty to defend ends\nwhen the limit has been paid out.\n\n**Coverage F, medical payments to others.**\
  \ We pay the necessary medical expenses, within three years of\nan accident, of a person who is hurt\
  \ on the residence premises with an insured's permission, or hurt\nelsewhere by what an insured or an\
  \ insured's animal does. This does not apply to you or to people who live\nin your household.\n\n**We\
  \ do not cover** under Part 7: injury or damage that an insured intends; anything arising out of a\n\
  business; the ownership or use of a motor vehicle, an aircraft, or a boat with a motor of more than\
  \ 25\nhorsepower; liability you take on under a contract, except a written lease; damage to property\
  \ an insured\nowns; or the passing on of a communicable disease.\n\n**We also pay** the costs of a suit\
  \ we defend; interest on a judgment; the cost of first aid to others\nat the time of an accident; and\
  \ up to $1,000.00 for damage an insured does to someone else's property,\nwhoever is at fault.\n\n**If\
  \ there is a claim under Part 7,** the insured must give us written notice as soon as practical, with\n\
  the time, place and names of those hurt and of witnesses; send us at once every letter, summons or other\n\
  paper that arrives; help us to settle or defend; and not make any payment or promise, except for first\n\
  aid, without our consent. Bankruptcy of an insured does not relieve us of our duties. The Coverage E\
  \ limit\nis the most we pay for one occurrence however many insureds, claims or injured people there\
  \ are.\n\n### Part 8. Conditions for the whole policy\n\n**8.1 Concealment or fraud.** The whole policy\
  \ is void for an insured who, before or after a loss, has on\npurpose hidden or misstated a fact that\
  \ matters.\n\n**8.2 Changes.** Only a written endorsement from us changes this policy. If we broaden\
  \ a form at no added\npremium during the policy period, you have the broader cover from the day it takes\
  \ effect in Wisconsin.\n\n**8.3 Cancelling.** You may cancel at any time by writing to us. We may cancel\
  \ for unpaid premium with 10\ndays' notice. After the policy has been in force 60 days we may otherwise\
  \ cancel only for a material\nmisstatement or a large change in the risk, with 30 days' notice.\n\n\
  **8.4 Not renewing.** If we decide not to renew, we will mail you notice at least 60 days before the\
  \ end\nof the policy period.\n\n**8.5 Your death.** If you die, we insure your legal representative\
  \ for the premises and property covered\nat the time of death, and the members of your household while\
  \ they go on living there.\n\n**8.6 Mutual company.** You are a member of Driftless Mutual Insurance\
  \ Company while this policy is in\nforce and may vote at the annual meeting, held on the second Tuesday\
  \ of March at our office in Viroqua.\nThis policy is not assessable.\n\n## Endorsements\n\n**DM-WB,\
  \ water backup and sump overflow.** We pay up to $25,000.00 for direct loss caused by water that\nbacks\
  \ up through a sewer or drain, or that overflows from a sump even if the pump has failed. The\ndeductible\
  \ for this cover is $1,000.00. It does not cover flood or surface water.\n\n**DM-SL, underground service\
  \ lines.** We pay up to $10,000.00 to repair or replace a water, sewer, gas or\nelectric line that you\
  \ own and that fails underground on the residence premises, with the digging and the\nmaking good of\
  \ the lawn and walks. The deductible for this cover is $500.00.\n\n**DM-RS, roof surfaces.** Loss to\
  \ the roof surface by wind or hail is settled at replacement cost with no\nallowance for age, in place\
  \ of any schedule that would otherwise apply.\n\n**DM-TR, residence held in trust.** The named insured\
  \ is the trustees of the trust in the Declarations.\nRaymond C. Ostrander and Margaret A. Ostrander,\
  \ who live in the dwelling, are insureds as though they were\nnamed in their own right. Tell us within\
  \ 60 days if the trustees change or the trust comes to an end.\n\n**DM-WI, Wisconsin changes.** Where\
  \ a term of this policy is in conflict with the statutes of Wisconsin,\nthe statute applies.\n\nCountersigned\
  \ at Viroqua, Wisconsin, February 9, 2026. <span class=\"sig\">Dale R. Hegge</span>, Secretary\n\n##\
  \ Notices that come with your policy\n\n**Your renewal.** Coverage A was raised by 4% at this renewal,\
  \ from $421,000.00 to $438,000.00, to keep\npace with the cost of building, and Coverages B, C and D\
  \ rose in step. At your request the deductible for\nperils other than wind and hail was changed from\
  \ $1,000.00 to $1,500.00. The water backup limit was raised\nfrom $10,000.00 to $25,000.00 and the service\
  \ line endorsement was added.\n\n**Discounts on this policy.** No claims in the past ten years; a central-station\
  \ burglar and fire alarm;\na roof less than ten years old; and an automobile policy with us.\n\n**To\
  \ report a claim** call (855) 555-0112 at any hour, or your agent during office hours. Have the policy\n\
  number, the date of the loss and a telephone number where you can be reached. Do not throw away damaged\n\
  property until our adjuster has seen it or has told you that you may.\n\n**If you are away in winter,**\
  \ read condition 6.4 before you leave. Members who spend part of the winter\nelsewhere are asked to\
  \ leave with a neighbor or relative the name of their agent and of a plumber and a\nheating contractor.\n\
  \n**If you have a complaint** that we have not been able to settle, you may write to the Wisconsin Office\
  \ of\nthe Commissioner of Insurance. We will send you the address on request.\n"