Harborline HO policy 2026-27 FULL
documentlook: clean
style: agreement11 pages render unknown
Text layer
9597 words
9597 words on 11 pages, from pdftotext. This is what search finds in the file.
Show the text
PO Box 4410
Columbus, OH 43216
Harborline Mutual Insurance
(800) 555-0142
harborline.example
HOMEOWNERS POLICY
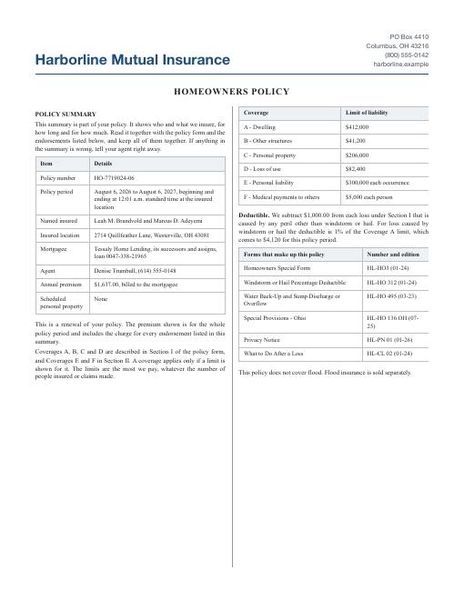
POLICY SUMMARY Coverage Limit of liability
This summary is part of your policy. It shows who and what we insure, for A - Dwelling $412,000
how long and for how much. Read it together with the policy form and the
endorsements listed below, and keep all of them together. If anything in B - Other structures $41,200
the summary is wrong, tell your agent right away.
C - Personal property $206,000
Item Details
D - Loss of use $82,400
Policy number HO-7719024-06
E - Personal liability $300,000 each occurrence
Policy period August 6, 2026 to August 6, 2027, beginning and
ending at 12:01 a.m. standard time at the insured F - Medical payments to others $5,000 each person
location
Deductible. We subtract $1,000.00 from each loss under Section I that is
Named insured Leah M. Brandvold and Marcus D. Adeyemi caused by any peril other than windstorm or hail. For loss caused by
windstorm or hail the deductible is 1% of the Coverage A limit, which
Insured location 2714 Quillfeather Lane, Westerville, OH 43081
comes to $4,120 for this policy period.
Mortgagee Tessaly Home Lending, its successors and assigns,
loan 0047-338-21965 Forms that make up this policy Number and edition
Agent Denise Trumbull, (614) 555-0148 Homeowners Special Form HL-HO3 (01-24)
Annual premium $1,637.00, billed to the mortgagee Windstorm or Hail Percentage Deductible HL-HO 312 (01-24)
Scheduled None Water Back-Up and Sump Discharge or HL-HO 495 (03-23)
personal property Overflow
Special Provisions - Ohio HL-HO 136 OH (07-
This is a renewal of your policy. The premium shown is for the whole 25)
policy period and includes the charge for every endorsement listed in this
summary. Privacy Notice HL-PN 01 (01-26)
Coverages A, B, C and D are described in Section I of the policy form, What to Do After a Loss HL-CL 02 (01-24)
and Coverages E and F in Section II. A coverage applies only if a limit is
shown for it. The limits are the most we pay, whatever the number of
This policy does not cover flood. Flood insurance is sold separately.
people insured or claims made.
HOMEOWNERS SPECIAL FORM
Form HL-HO3 (01-24) separate from the Coverage A limit, and using it does not reduce what is
available for the dwelling.
AGREEMENT
Coverage C - Personal property. We cover personal property that an
This policy is a contract between you and us. You pay the premium when
insured owns or uses, anywhere in the world. After a loss, and if you ask
it is due and keep to the terms of the policy, and in return we provide the
us to, we will also cover personal property of a guest or a residence
insurance described in it. The policy is made up of the Policy summary,
employee while it is in a residence an insured occupies, and other people's
this form and the endorsements listed in the Policy summary. An
property while it is in the part of the residence premises an insured
endorsement changes this form, and where the two differ the endorsement
occupies. For personal property usually kept at a residence of an insured
controls. Section I covers your home and your belongings. Section II
other than the residence premises, the most we pay is 10% of the
covers your legal responsibility to other people.
Coverage C limit or $1,000, whichever is more.
DEFINITIONS
SPECIAL LIMITS OF LIABILITY
Some words have the same special meaning wherever they are used in
Some kinds of personal property are covered only up to a smaller amount.
this policy.
The limits below are part of the Coverage C limit, not in addition to it.
You and your mean the person or persons shown as named insured in the Each one is the most we will pay for any one loss for all the property in
Policy summary, and the spouse of a named insured if the spouse lives in that category, whatever the number of articles or of people who own them.
the same household. We, us and our mean Harborline Mutual Insurance.
$200 in total for money, bank notes, coins, bullion, medals, gift cards
Actual cash value means the cost, at the time of the loss, to repair or and other stored-value cards.
replace the property with property of like kind and quality, less a fair $1,500 in total for securities, deeds, accounts, evidences of debt,
allowance for its age, wear and obsolescence. letters of credit, manuscripts, passports, tickets and stamps, whether
Bodily injury means physical harm to a person, sickness or disease, on paper or stored electronically.
including the care it requires and death that results. $1,500 in total for watercraft of every kind, including their trailers,
furnishings, equipment and outboard motors.
Business means a trade, profession or occupation, whether full time, part
$1,500 in total for trailers and semitrailers that are not used with
time or occasional, and any other activity carried on for pay.
watercraft.
Insured means you and, if they live in your household, your relatives and $2,500 in total for loss by theft of firearms and related equipment.
any other person under 21 who is in your care or in the care of a relative $1,500 in total for loss by theft of jewelry, watches, furs, and
who lives with you. It includes a full-time student under 24 who lived in precious and semiprecious stones.
your household before moving away to attend school. $2,500 in total for loss by theft of silverware, silver-plated ware,
Insured location means the residence premises; any other premises you goldware, gold-plated ware and pewterware, including flatware,
use as a residence, if it is shown in the Policy summary or you acquire it hollowware, tea sets and trays.
during the policy period; premises an insured does not own but is living in $2,500 in total for property on the residence premises that is used
for a time; and vacant land, other than farm land, that an insured owns or mainly for business.
rents. $500 in total for property away from the residence premises that is
used mainly for business.
Occurrence means an accident that results, during the policy period, in
$1,500 in total for portable electronic equipment, such as a laptop
bodily injury or property damage. Continuous or repeated exposure to
computer, tablet or camera, while it is in or on a motor vehicle.
substantially the same harmful conditions is one occurrence.
$1,000 in total for trading cards, comic books, sports memorabilia
Property damage means physical injury to tangible property or its and other collectibles.
destruction, and the loss of its use that results.
These special limits can be raised only by scheduling the items on an
Residence employee means a person an insured employs to do household
endorsement to this policy, for an additional premium. The Policy
or domestic work, or other work connected with the upkeep or use of the
summary shows whether any personal property is scheduled.
residence premises.
PROPERTY WE DO NOT COVER UNDER COVERAGE C
Residence premises means the one to four family dwelling where you
live that is shown as the insured location in the Policy summary, together Articles that are separately described and specifically insured, in this
with the other structures and the grounds at that address. policy or in any other insurance.
Animals, birds and fish.
SECTION I - WHAT WE COVER Motor vehicles and their parts, equipment and accessories. We do
Coverage A - Dwelling. We cover the dwelling on the residence premises, cover vehicles that are not required to be registered for road use and
including structures attached to it, such as an attached garage, porch or are used to service an insured's residence or to assist a person with a
deck. We also cover materials and supplies on or next to the residence disability, such as a riding lawn mower or a motorized wheelchair.
premises that are meant for building, altering or repairing the dwelling or Property of roomers, boarders and other tenants, unless they are
other structures there. We do not cover land, including the land the related to an insured.
dwelling stands on. Business records and data, whether kept on paper, in a computer or
Coverage B - Other structures. We cover other structures on the on any other medium.
residence premises that are separated from the dwelling by clear space, or Credit cards, debit cards and other fund transfer cards, except as
joined to it only by a fence, a utility line or a similar connection. provided under Additional coverage 6.
Examples are a detached garage, a shed, a fence and a driveway. We do Coverage D - Loss of use. If a loss we cover under Section I makes the
not cover land; a structure rented or held for rental to anyone who is not a part of the residence premises where you live unfit to live in, we pay the
tenant of the dwelling, unless it is used only as a private garage; or a necessary increase in your living costs, so that your household can keep
structure used in whole or in part for a business. The Coverage B limit is up its normal standard of living. We pay for the shortest time needed to
repair or replace the damage or, if you move for good, for your household 9. Glass or safety glazing material. We cover the breakage of glass or
to settle somewhere else. If the loss makes a part of the residence safety glazing material that is part of a covered building, storm door or
premises that you rent out unfit to live in, we pay its fair rental value, less storm window, and direct damage to covered property done by the broken
any expenses that stop while it cannot be lived in. If a civil authority pieces. We do not cover this loss if the dwelling has been vacant for more
forbids you to use the residence premises because a peril we insure than 60 consecutive days immediately before the loss. A dwelling being
against has directly damaged a neighboring property, we pay these built is not considered vacant.
amounts for up to two weeks. The Coverage D limit is the most we pay 10. Ordinance or law. You may use up to 10% of the Coverage A limit
for everything in this coverage combined. for the increased cost you incur because an ordinance or law is enforced
SECTION I - ADDITIONAL COVERAGES that regulates the construction, demolition, remodeling or repair of the
part of a covered building damaged by a peril we insure against, or that
The coverages below are in addition to Coverages A to D. Unless a
requires the undamaged part to be torn down and rebuilt because of that
coverage says otherwise, the Section I deductible applies to it, it is subject
damage. We do not cover the loss in value of a building caused by the
to the exclusions and conditions of Section I, and it does not increase the
requirements of a law. This coverage is additional insurance.
limit of liability that applies to the damaged property.
1. Debris removal. We pay your reasonable cost to remove the debris of SECTION I - PERILS WE INSURE AGAINST
covered property after a loss caused by a peril we insure against. This cost Coverage A - Dwelling and Coverage B - Other structures. We cover
is part of the limit that applies to the damaged property. If the damage and direct physical loss to the property described under Coverages A and B
the debris removal together come to more than that limit, a further 5% of from any cause, unless the loss is listed below under Losses we do not
the limit is available for debris removal. cover or is excluded under Section I - Exclusions.
2. Reasonable repairs. If a peril we insure against damages covered Coverage C - Personal property. We cover direct physical loss to the
property, we pay the reasonable cost of the measures you have to take just property described under Coverage C only when it is caused by one of the
to protect the property from further damage, such as boarding up a perils listed here, and only if the loss is not listed below under Losses we
window or putting a tarp over an opening. do not cover or excluded under Section I - Exclusions.
3. Trees, shrubs and other plants. We cover trees, shrubs, plants and Fire or lightning.
lawns on the residence premises for loss caused by fire, lightning, Windstorm or hail. This does not include loss to property inside a
explosion, riot, civil commotion, aircraft, a vehicle not owned or driven building caused by rain, snow, sleet, sand or dust, unless the direct
by someone who lives on the residence premises, vandalism, malicious force of wind or hail first damages the building and makes an
mischief or theft. We pay up to 5% of the Coverage A limit for all of them opening in a roof or wall through which it gets in.
together, and no more than $500 for any one tree, shrub or plant. This Explosion.
coverage is additional insurance. Riot or civil commotion.
4. Fire department service charge. We pay up to $500 for charges you Aircraft, including self-propelled missiles and spacecraft.
have agreed by contract to pay when a fire department is called to save or Vehicles.
protect covered property from a peril we insure against. This coverage is Smoke, meaning sudden and accidental damage from smoke,
additional insurance and no deductible applies to it. including soot or fumes released when a furnace, boiler or similar
equipment malfunctions.
5. Property removed. Covered property that is moved from a place Vandalism or malicious mischief.
endangered by a peril we insure against is covered for direct loss from any Theft, including attempted theft. Property that is gone from a known
cause while it is being moved and for up to 30 days while it is away. place is treated as stolen when the circumstances make it likely that
6. Credit card, fund transfer card, forgery and counterfeit money. We someone took it. Theft does not include mysterious disappearance,
pay up to $500 for: what an insured legally owes because a credit card that is, the loss of property from a known place when it is likely that
issued to the insured was stolen or used without permission; loss to an the property was simply lost or misplaced. Nor does it include theft
insured from the theft or unauthorized use of a debit card or other fund committed by an insured; theft from a part of the residence premises
transfer card; loss from the forgery or alteration of a check; and loss from that an insured rents to someone who is not an insured; or theft of
accepting counterfeit United States or Canadian paper currency in good property at any other residence owned by, rented to or occupied by
faith. We do not cover use of a card by a person who lives in your an insured, unless an insured is living there for a time.
household or whom an insured has entrusted with the card, or loss that Falling objects. This does not include loss to property inside a
arises from a business or from the dishonesty of an insured. No deductible building unless the falling object first damages the roof or an outside
applies. wall.
7. Loss assessment. We pay up to $1,000 for your share of a loss Weight of ice, snow or sleet that damages property inside a building.
Accidental discharge or overflow of water or steam from within a
assessment that an association of property owners charges you, during the
plumbing, heating, air-conditioning or fire-protective sprinkler
policy period, as the owner of the residence premises, when the
assessment is made because of direct loss to property owned in common system or a household appliance. This does not include loss to the
system or appliance the water or steam came from. A sump, a sump
by the members and caused by a peril we insure against under Coverage
pump and its related equipment, and a roof drain, gutter or
A. The $1,000 is the most we pay for any one loss, however many
assessments follow from it. downspout are not plumbing systems or household appliances.
Sudden and accidental tearing apart, cracking, burning or bulging of
8. Collapse. Collapse means that a building or a part of a building a steam or hot water heating system, an air-conditioning or fire-
suddenly falls down or caves in, so that it cannot be used for its intended protective sprinkler system, or an appliance for heating water.
purpose. A building that is only in danger of falling, or that is still Freezing of a plumbing, heating, air-conditioning or fire-protective
standing though it shows cracking, bulging, sagging, leaning or settling, sprinkler system or of a household appliance, within the terms set out
has not collapsed. We cover direct physical loss to covered property under Losses we do not cover.
involving collapse only if the collapse was caused by: a peril listed under Sudden and accidental damage from artificially generated electrical
Coverage C; hidden decay, or hidden insect or vermin damage, that no current.
insured knew of before the collapse; the weight of contents, equipment,
animals or people; or the weight of rain that collects on a roof.
Volcanic eruption, other than loss caused by earthquake, land shock or related equipment; and water below the surface of the ground,
waves or tremors. including water that presses on, seeps or leaks through a building,
sidewalk, driveway, foundation or other structure. This policy does
Losses we do not cover. Under Coverages A, B and C we do not cover not cover flood. Flood insurance is sold separately, and your agent
loss caused by any of the following. can tell you how to buy it. If fire, explosion or theft follows, we
Collapse, other than as provided under Additional coverage 8. cover the direct loss caused by the fire, explosion or theft.
Freezing, thawing, or the pressure or weight of water or ice, whether Power failure. The failure of power or another utility service, if the
or not driven by wind, to a fence, pavement, patio, swimming pool, failure takes place away from the residence premises. If the failure
foundation, retaining wall, pier or dock. leads to a loss on the residence premises from a peril we insure
Freezing of a plumbing, heating, air-conditioning or sprinkler system against, we cover the loss caused by that peril.
or of a household appliance, or discharge, leakage or overflow from Neglect. The failure of an insured to use all reasonable means to save
within the system or appliance because of freezing, while the and protect property at the time of a loss and afterwards.
dwelling is vacant, unoccupied or being built, unless you have used War. War, whether declared or not, civil war, insurrection, rebellion
reasonable care to maintain heat in the building, or to shut off the or revolution; a warlike act by a military force; and the destruction,
water supply and drain the systems and appliances. seizure or use of property for a military purpose. The discharge of a
Theft in or to a dwelling being built, or of materials and supplies nuclear weapon is treated as a warlike act even if it is accidental.
meant for building it, until the dwelling is finished and occupied. Nuclear hazard. Nuclear reaction, radiation or radioactive
Vandalism or malicious mischief, and any damage done on purpose contamination, however caused. We do cover direct loss by fire that
in the course of it, if the dwelling has been vacant for more than 60 results from the nuclear hazard.
consecutive days immediately before the loss. A dwelling being built Intentional loss. Any loss that arises from an act an insured
is not considered vacant. commits, or conspires with others to commit, with the intent to cause
Constant or repeated seepage or leakage of water or steam, or the a loss. When this exclusion applies, no insured is entitled to
presence of humidity, moisture or vapor, over a period of weeks, coverage, including an insured who took no part in the act.
months or years. Governmental action. The destruction, confiscation or seizure of
Mold, fungus, wet rot or dry rot, unless it is hidden within walls or property by order of a governmental or public authority.
ceilings or beneath floors and results from the accidental discharge or Faulty work and planning. Under Coverages A and B, faulty or
overflow of water or steam from within a plumbing, heating, air- inadequate planning, zoning, design, workmanship, construction,
conditioning or sprinkler system or a household appliance on the grading, materials or maintenance, of any property on or off the
residence premises. residence premises. If a loss that is not otherwise excluded follows,
Smoke from agricultural smudging or industrial operations. we cover that loss.
The discharge, release, seepage or escape of pollutants, unless it is
itself caused by a peril listed under Coverage C. SECTION I - CONDITIONS
Wear and tear, marring, scratching and deterioration; mechanical 1. Insurable interest and limit of liability. Even when more than one
breakdown; a defect or quality in property that causes it to damage or person has an insurable interest in the covered property, in any one loss
destroy itself; smog, rust and other corrosion. we will not pay an insured more than the amount of that insured's interest
Settling, shrinking, bulging or expansion, and the cracking that at the time of the loss, and we will not pay more than the limit of liability
results, of pavements, patios, foundations, walls, floors, roofs or that applies.
ceilings. 2. Deductible. Unless this policy says otherwise, we pay only the part of
Birds, rodents, insects and other vermin; and animals owned or kept a covered loss that is more than the deductible shown in the Policy
by an insured. summary. If two or more deductibles could apply to the same loss, only
the largest applies.
If a cause named in the last three items makes water escape suddenly and
accidentally from a plumbing, heating, air-conditioning or sprinkler 3. Your duties after a loss. After a loss to covered property, you must see
system or a household appliance, we cover the loss the water causes, that the following things are done. If they are not done and we are harmed
including the cost of tearing out and replacing any part of a building when as a result, we do not have to provide coverage for the loss.
that is needed to repair the system or appliance. We do not cover the loss (a) Tell us or your agent promptly.
to the system or appliance itself.
(b) Tell the police if the loss is by theft, and tell the card issuer or the bank
SECTION I - EXCLUSIONS if a credit card or fund transfer card is involved.
We do not cover loss caused directly or indirectly by any of the following. (c) Protect the property from further damage. Make the reasonable and
The loss is excluded whatever other cause or event contributes to it, at the necessary repairs that protect it, and keep a record of what you spend.
same time or in any order, and whether the event is local or widespread.
(d) Cooperate with us while we look into the claim.
Ordinance or law. The enforcement of any ordinance or law that
(e) Make a list of the damaged and missing personal property that shows
regulates the construction, repair or demolition of a building or other
the quantity, description, actual cash value and amount of loss for each
structure, and any loss in value that results. Additional coverage 10 is
item, and attach the bills, receipts and other papers that support the
the only exception.
figures.
Earth movement. Earthquake; landslide, mudslide or mudflow;
subsidence or sinkhole; and any other sinking, rising or shifting of (f) As often as we reasonably ask: show us the damaged property; give us
the earth, whether it comes about naturally or through human the records and documents we ask for and let us copy them; and answer
activity. If fire or explosion follows, we cover the direct loss caused questions under oath, apart from any other insured, and sign the record of
by the fire or explosion. your answers.
Flood and other water. Flood, surface water, waves, tidal water, the (g) Send us your signed, sworn proof of loss within 60 days after we ask
overflow of a body of water, and spray from any of these, whether or for it. The proof of loss must state, as far as you know, the time and cause
not driven by wind; water or sewage that backs up through sewers or of the loss, the interest that each insured and anyone else has in the
drains, or that overflows or is discharged from a sump, sump pump
property, and any other insurance that may cover the loss. It must include cancellation or nonrenewal takes effect. If we pay the mortgagee for a loss
repair estimates for damaged buildings and the list described in (e). and deny payment to you, we take over the mortgagee's rights under the
4. How we settle losses. Covered property losses are settled as follows. mortgage to the extent of our payment.
(a) Personal property, carpeting, household appliances, awnings, outdoor SECTION II - LIABILITY COVERAGES
equipment and structures that are not buildings: at actual cash value at the Coverage E - Personal liability. If a claim is made or a suit is brought
time of the loss, but not more than the amount needed to repair or replace against an insured for damages because of bodily injury or property
them. damage caused by an occurrence that this coverage applies to, we will
(b) Buildings under Coverage A or B: at replacement cost, without a pay, up to our limit of liability, the damages the insured is legally
deduction for depreciation. If, at the time of the loss, the amount of obligated to pay. We will also provide a defense at our expense with a
insurance on the damaged building is 80% or more of its full replacement lawyer we choose, even if the suit has no basis. We may investigate any
cost, we pay the cost to repair or replace the damaged part, but not more claim or suit and settle it as we think fit. Our duty to settle or defend ends
than the least of: the limit of liability that applies to the building; the when the amount we have paid in judgments or settlements for the
replacement cost of the damaged part with materials of like kind and occurrence equals our limit of liability.
quality; or the amount actually and necessarily spent. If the amount of Coverage F - Medical payments to others. We pay the necessary
insurance is less than 80% of the full replacement cost, we pay the greater medical expenses that are incurred within three years after an accident
of the actual cash value of the damaged part, or that share of the cost to that causes bodily injury, whether or not anyone was at fault. Medical
repair or replace it which the amount of insurance on the building bears to expenses are reasonable charges for medical, surgical, x-ray and dental
80% of its replacement cost. care, ambulance, hospital and nursing services, prosthetic devices and
(c) We pay no more than the actual cash value of the damage until the funeral services. This coverage is for other people. It does not apply to
repair or replacement is finished. You may claim on an actual cash value you or to anyone who regularly lives in your household, other than a
basis first and then claim the difference, if you tell us within 180 days residence employee. It applies to a person who is on an insured location
after the date of the loss that you intend to repair or replace the building. with the permission of an insured, and to a person away from an insured
location if the bodily injury arises from a condition on the insured
5. Appraisal. If you and we do not agree on the amount of a loss, either of
location, is caused by something an insured or a residence employee does,
us may ask in writing for an appraisal. Each of us then chooses a or is caused by an animal that an insured owns or is looking after.
competent and impartial appraiser within 20 days after receiving the
request, and the two appraisers choose an umpire. If they cannot agree on SECTION II - EXCLUSIONS
one within 15 days, you or we may ask a judge of a court of record to 1. Coverage E and Coverage F do not apply to bodily injury or property
choose the umpire. The appraisers each set the amount of the loss. If they damage:
do not agree, they submit their differences to the umpire, and a decision
that an insured expects or intends, even if the injury or damage turns
agreed to by any two of the three sets the amount. Each of us pays the
out to be of a different kind or degree than expected. This does not
appraiser we chose, and we share the other costs equally. An appraisal
apply to bodily injury that results from the use of reasonable force to
decides only the amount of a loss. It does not decide whether the loss is
protect people or property;
covered.
that arises from a business an insured is engaged in, or from the
6. Other insurance. If a loss covered by this policy is also covered by rental of any part of any premises by an insured;
other insurance, we pay only our share, which is the proportion that the that arises from providing or failing to provide professional services;
limit of liability under this policy bears to the total amount of insurance that arises from premises that an insured owns, rents or rents out to
covering the loss. others and that are not an insured location;
7. Suit against us. You may not bring a suit against us under Section I that arises from the ownership, maintenance or use of a motor
unless you have complied with all the terms of this policy that apply to vehicle, an aircraft, or a watercraft with engine power of more than
Section I, and the suit is started within one year after the date of the loss. 50 horsepower or a length of 26 feet or more. This does not apply to
a vehicle not subject to registration that is used to service an insured's
8. Our option. We may repair or replace any part of the damaged
residence or to assist a person with a disability, or to a model or
property with material or property of like kind and quality, if we give you
hobby aircraft not built to carry people or cargo;
written notice that we will do so within 30 days after we receive your
that is caused directly or indirectly by war, as described in the war
signed, sworn proof of loss.
exclusion of Section I;
9. Loss payment. We settle all losses with you. We pay you, unless that arises from sexual molestation, corporal punishment, or physical
another person is named in this policy or is legally entitled to receive the or mental abuse; or
payment. A loss becomes payable 30 days after we receive your proof of that arises from the use, sale, manufacture or possession of a
loss and one of these has happened: you and we have reached agreement; controlled substance, other than the legitimate use of prescription
a final judgment has been entered; or an appraisal award has been filed drugs as a licensed physician directs.
with us.
2. Coverage E does not apply to:
10. Abandonment of property. We do not have to accept any property
that an insured abandons to us. liability for a loss assessment charged against you as a member of an
association of property owners;
11. Mortgage clause. If a mortgagee is named in the Policy summary, a
liability an insured takes on under a contract or agreement, other than
loss payable under Coverage A or B is paid to the mortgagee and to you,
a written contract that relates directly to the ownership, maintenance
as your interests appear. If we deny your claim, the denial does not apply
or use of an insured location;
to a valid claim of the mortgagee, provided the mortgagee tells us of any
property damage to property an insured owns;
change in ownership or occupancy, or any substantial change in risk, that
property damage to property that is rented to, occupied by, used by or
it knows about; pays any premium due on demand if you have failed to
in the care of an insured, unless it is caused by fire, smoke or
pay it; and sends us a signed, sworn proof of loss within 60 days after we
explosion;
notify it that you have failed to do so. If we decide to cancel this policy or
bodily injury to a person who is eligible to receive benefits that an
not to renew it, we will notify the mortgagee at least 10 days before the
insured provides, or is required to provide, under a workers'
compensation or disability law; or to apply in excess of the limits of this policy.
bodily injury to you or to any other insured.
CONDITIONS THAT APPLY TO SECTIONS I AND II
3. Coverage F does not apply to bodily injury: 1. Policy period. This policy applies only to loss under Section I, and to
to a residence employee, if the injury happens away from the insured bodily injury or property damage under Section II, that happens during
location and does not arise out of the employee's work for an insured; the policy period shown in the Policy summary.
to a person who is eligible to receive benefits under a workers' 2. Concealment or fraud. We do not provide coverage to an insured who,
compensation or disability law; or before or after a loss, has intentionally concealed or misrepresented a
to a person, other than a residence employee, who regularly lives on material fact or circumstance, has engaged in fraudulent conduct, or has
any part of the insured location. made false statements, in connection with this insurance.
SECTION II - ADDITIONAL COVERAGES 3. Waiver or change of policy terms. A term of this policy can be waived
We pay the following in addition to the limits of liability. or changed only in writing by us. Our asking for an appraisal or an
examination does not waive any of our rights.
1. Claim expenses. We pay the expenses we incur and the costs charged
against an insured in a suit we defend; reasonable expenses an insured 4. Cancellation. You may cancel this policy at any time by returning it to
incurs at our request, including actual loss of earnings of up to $250 a day, us or by telling us in writing the date on which the cancellation is to take
for helping us investigate or defend a claim or suit; and interest on a effect. We may cancel only for the reasons below, by notifying you in
judgment that builds up after the judgment is entered and before we pay writing of the date the cancellation takes effect. We may deliver the notice
the part of it that is within our limit of liability. to you or mail it to you at the mailing address we have on record, and
proof of mailing is sufficient proof of notice.
2. First aid expenses. We pay the expenses an insured incurs for first aid
to others at the time of bodily injury covered by this policy. (a) If you have not paid the premium, we may cancel at any time by
notifying you at least 10 days before the cancellation takes effect.
3. Damage to property of others. We pay, at replacement cost, up to
$1,000 for each occurrence for property damage to property of others (b) If this policy has been in effect for less than 60 days and is not a
caused by an insured. We do not pay for property damage caused on renewal, we may cancel for any reason by notifying you at least 30 days
purpose by an insured who is 13 or older; to property owned by an before the cancellation takes effect.
insured or by a person who lives in your household; or that arises from a (c) If this policy has been in effect for 60 days or more, or is a renewal,
business or from the ownership, maintenance or use of an aircraft, we may cancel if there has been a material misrepresentation of fact that
watercraft or motor vehicle. would have led us not to issue the policy had we known of it, or if the risk
has changed substantially since the policy was issued. We do so by
SECTION II - CONDITIONS
notifying you at least 30 days before the cancellation takes effect.
1. Limit of liability. The Coverage E limit shown in the Policy summary
When this policy is cancelled, the premium for the time from the date of
is the most we pay for all damages that result from any one occurrence,
cancellation to the expiration date is refunded pro rata.
whatever the number of insureds, claims made or people injured. The
Coverage F limit is the most we pay for all medical expenses for bodily 5. Nonrenewal. We may decide not to renew this policy. If so, we will
injury to one person as the result of one accident. deliver to you, or mail to you at the mailing address we have on record,
written notice at least 30 days before the expiration date.
2. Separate insurance. This insurance applies separately to each insured.
That does not increase our limit of liability for any one occurrence. 6. Assignment. You may not assign this policy to anyone else unless we
agree to it in writing.
3. Duties after an occurrence. When an accident or occurrence happens,
you or another insured must give written notice to us or your agent as 7. Subrogation. Before a loss, an insured may give up in writing all rights
soon as practical, saying what is known of the time, place and to recover from any person. If those rights have not been given up, we
circumstances and giving the names and addresses of claimants and may require the insured to assign to us the rights of recovery for a loss, to
witnesses; send us promptly every notice, demand, summons or other the extent of what we have paid.
legal paper that has to do with it; and, when we ask, help us to make a 8. Death. If a person named in the Policy summary dies, we insure the
settlement, to conduct suits and to secure evidence and witnesses. legal representative of that person, but only for the premises and property
4. Duties of an injured person - Coverage F. The injured person, or of that person that this policy covered at the time of death.
someone acting for the injured person, must give us written proof of the 9. Mutual membership. While this policy is in force you are a member
claim as soon as practical, authorize us to obtain copies of medical reports of Harborline Mutual Insurance and may vote, in person or by proxy, at
and records, and agree to be examined by a doctor we choose as often as meetings of the members. The annual meeting is held at our home office
we reasonably require. in Columbus, Ohio, on the second Tuesday of March at 10:00 a.m. This
5. Suit against us. No one may bring a suit against us under Section II policy is non-assessable: you are not liable for any amount beyond the
unless the terms of this policy have been complied with. No suit may be premium.
brought against us under Coverage E until the insured's obligation has We have had this policy signed by our president and our secretary. It is not
been settled by a final judgment or by an agreement that we have signed. valid unless a Policy summary issued by us is attached.
R. Achterberg President T. Wenlock Secretary
6. Other insurance - Coverage E. This insurance is excess over any
other valid and collectible insurance, except insurance written specifically
WINDSTORM OR HAIL PERCENTAGE DEDUCTIBLE
Form HL-HO 312 (01-24) WHEN IT APPLIES
This endorsement changes your policy. Please read it carefully and keep it The windstorm or hail deductible applies to the total of all loss payable
with your policy. under Section I, under Coverages A, B, C and D and the Additional
coverages together, that is caused directly or indirectly by windstorm or
Schedule This policy hail in one event. Windstorm includes tornado and straight-line wind, with
or without rain. All windstorm or hail damage that takes place within a
Policy number HO-7719024-06
period of 72 hours is treated as one event.
Coverage A limit of liability $412,000 For such a loss, the windstorm or hail deductible applies instead of the
$1,000.00 deductible shown in the Policy summary. It is not added to it.
Windstorm or hail deductible, as a percentage 1% We subtract one deductible from the loss, never both, and no other
deductible in this policy applies to loss caused by windstorm or hail.
Windstorm or hail deductible, in dollars $4,120
If the same event causes loss by windstorm or hail and also loss by
WHAT THIS ENDORSEMENT DOES another peril we insure against, such as a fire started by lightning in the
same storm, only the windstorm or hail deductible applies to that event.
Your policy has two Section I deductibles. One applies to loss caused by
windstorm or hail and is set by this endorsement. The other is shown in TWO EXAMPLES
the Policy summary and applies to loss caused by every other peril we A hailstorm damages the siding and gutters of the dwelling and dents a
insure against. detached shed. The covered loss comes to $15,000. We subtract $4,120
HOW THE DEDUCTIBLE IS WORKED OUT and pay $10,880.
The windstorm or hail deductible is a percentage of the Coverage A limit A windstorm brings a limb down on a fence. The covered loss comes to
of liability. It is not a percentage of the loss. We multiply the Coverage A $2,900. That is less than the windstorm or hail deductible, so no payment
limit in force at the time of the loss by the percentage shown in the is due.
schedule. On this policy that is 1% of $412,000, or $4,120. If the This endorsement changes only the deductible. All other terms of the
Coverage A limit is changed during the policy period, the dollar amount policy stay the same.
of this deductible changes with it from the date the change takes effect.
WATER BACK-UP AND SUMP DISCHARGE OR OVERFLOW
Form HL-HO 495 (03-23) The Section I deductible that applies to perils other than windstorm or
This endorsement changes your policy. Please read it carefully and keep it hail, $1,000.00, applies to each loss under this endorsement. We subtract
with your policy. it from the amount of the covered loss and then apply the limit. The
windstorm or hail deductible does not apply to this coverage.
Schedule This policy
WHAT THIS ENDORSEMENT DOES NOT COVER
Policy number HO-7719024-06 Loss to the sump pump or its related equipment that is caused by
mechanical breakdown.
Limit of liability for this coverage $10,000 for any one loss Loss caused by flood, surface water, waves, tidal water or the
overflow of a body of water, even if that water comes in through a
Deductible $1,000.00 for each loss
sewer or drain or is more than a sump can handle. This policy does
Premium Included in the annual premium not cover flood.
Loss caused by water below the surface of the ground that presses
on, seeps or leaks through a foundation, wall or floor, other than
COVERAGE
water that a sump collects and that then overflows or is discharged
We pay up to the limit shown in the schedule for sudden and accidental from the sump.
direct physical loss to property covered under Section I that is caused by Loss that results from a failure to do what is reasonable to keep the
water, or by material carried in the water, which backs up through sewers sump pump and the drains on the residence premises in working
or drains, or which overflows or is discharged from a sump, sump pump order.
or related equipment. We cover the overflow or discharge even when it
results from the mechanical breakdown of the pump or from a power CHANGE TO THE EXCLUSIONS
failure, on or off the residence premises. The part of the Flood and other water exclusion in Section I that deals
with water or sewage that backs up through sewers or drains, or that
LIMIT AND DEDUCTIBLE
overflows or is discharged from a sump, sump pump or related
The limit in the schedule is the most we pay for any one loss covered by equipment, does not apply to the coverage this endorsement provides. The
this endorsement, under Coverages A, B, C and D combined. It includes rest of that exclusion is unchanged.
the cost of removing the water and the debris, and of cleaning and drying
out the property. It is part of the limits of liability for Coverages A, B, C AFTER A BACK-UP OR OVERFLOW
and D, not in addition to them. Your duties after a loss apply. The reasonable cost of the measures you
take to keep the damage from growing counts toward the limit in the
schedule. All other terms of the policy stay the same.
SPECIAL PROVISIONS - OHIO
Form HL-HO 136 OH (07-25)
SECTION II - EXCLUSIONS
This endorsement changes your policy so that it meets the requirements
1. Coverage E and Coverage F. The following is added. Coverages E
that apply to homeowners insurance in Ohio. Where it differs from the
and F do not apply to bodily injury or property damage that arises from
policy form, this endorsement controls. The numbers below are those of
child care or adult day care that an insured regularly provides for pay, at
the paragraphs they change.
an insured location, to people who are not insureds.
SECTION I - EXCLUSIONS 2. Coverage E. The following is added. Coverage E does not pay punitive
Intentional loss is replaced by the following. We do not cover a loss that or exemplary damages, fines or penalties.
arises from an act an insured commits, or conspires with others to
CONDITIONS THAT APPLY TO SECTIONS I AND II
commit, with the intent to cause a loss. An insured who took no part in the
act and did not know of it beforehand may still recover for his or her own 2. Concealment or fraud. The following is added. Ohio law makes it a
interest in the property, up to the limit of liability, if the loss arose from an crime to give an insurer an application or a claim containing a statement
act of domestic violence against that insured, and that insured reports the that the person knows to be false or deceptive, with the intent to defraud.
act to a law enforcement agency and cooperates in any investigation of the 4. Cancellation. The following is added. Our notice of cancellation will
loss. We may then recover what we pay from the insured who caused the state the reason for it. The notice periods in paragraphs (a), (b) and (c) are
loss. not changed.
SECTION I - CONDITIONS 5. Nonrenewal. The following is added. Our notice of nonrenewal will
4. How we settle losses. The following is added. When we repair or state the reason for it.
replace part of a building and the new materials do not reasonably match 7. Subrogation. The following is added. We are entitled to recover from
the adjoining undamaged materials in quality, color or size, we will another party only after you have been fully compensated for your loss.
replace as much of the adjoining area as is needed to give a reasonably
ADDED CONDITIONS
uniform appearance.
10. Conformity with Ohio law. Any term of this policy that conflicts
5. Appraisal. The following is added. Each of us pays our own lawyers
with the laws of Ohio is changed to conform to those laws.
and expert witnesses.
11. Mine subsidence. This policy does not cover loss caused by the
9. Loss payment. The last sentence is replaced by the following. We will
collapse of an underground mine or by the movement of the ground above
tell you in writing whether we accept or deny your claim within 21 days
one. That coverage is provided only by a mine subsidence endorsement,
after we receive a properly completed proof of loss. If we need more time
where one is available, and only if the endorsement is listed in the Policy
to look into the claim, we will tell you why within those 21 days and will
summary.
write to you again at least every 45 days until we decide. Once we have
accepted a claim and the amount is agreed, set by a final judgment or set 12. Questions and complaints. If you have a question about this policy
by an appraisal award filed with us, we will pay within 10 days. or are not satisfied with how a claim or a request has been handled, call
your agent or call us at (800) 555-0142. If we cannot resolve the matter,
you may contact the consumer services division of the state department of
insurance.
All other terms of the policy stay the same.
PRIVACY NOTICE
Form HL-PN 01 (01-26) your mortgagee and any other party named in your policy;
We send this notice when a policy is issued and at each renewal. It adjusters, appraisers, contractors, lawyers and other firms that help
explains what personal information Harborline Mutual Insurance collects us handle a claim or run our business. They must keep the
about you, how we use and protect it, and what you can do about it. It is a information confidential and use it only for the work we give them;
notice only. It is not part of the insurance contract and it does not change reinsurers and auditors;
your coverage. insurance support organizations and other insurers, to report claims
and to detect and prevent fraud; and
WHAT WE COLLECT regulators, courts and law enforcement agencies, when the law
We collect only the information we need to quote, issue and service your requires it.
policy and to handle claims.
HOW WE PROTECT IT
From you and your agent: your name, address, date of birth, phone Access to your personal information is limited to the employees and
number and e-mail address, the names of the people in your agents who need it to do their work. We keep physical, electronic and
household, and facts about the property you ask us to insure.
procedural safeguards, and we train our staff in how to handle personal
From your dealings with us: the coverages you have chosen, your information. We keep records only as long as our business or the law
premium and payment record, and the details of any claim made requires and then destroy them securely.
under your policy.
From others: reports from consumer reporting agencies, including YOUR RIGHTS
credit-based insurance scores where the law allows them; property You may ask us in writing what personal information we hold about you,
and loss information from inspection services and insurance support and you may see and copy it. You may ask us to correct, amend or delete
organizations; and public records. anything you believe is wrong. We will answer within 30 business days. If
we do not agree to a change, you may send us a short statement of what
HOW WE USE IT
you dispute and why. We will keep the statement with your file.
We use personal information to underwrite and price your policy, to bill
and collect the premium, to investigate and settle claims, to prevent and HOW TO REACH US
detect fraud, to meet our legal and regulatory duties, and to improve our Write to the Privacy Office, Harborline Mutual Insurance, PO Box 4410,
service. Columbus, OH 43216, call (800) 555-0142, or go to
harborline.example/privacy. Please give your name, your address and
WHO WE SHARE IT WITH
your policy number.
We do not sell your personal information, and we do not share it with
other companies so that they can market their products to you. We share it CHANGES TO THIS NOTICE
only as the law permits and only as far as is needed, with: We may change our privacy practices. If a change affects how we share
your agent; your personal information, we will send you a new notice before the
change takes effect.
WHAT TO DO AFTER A LOSS
Form HL-CL 02 (01-24) IF YOU DISAGREE WITH US
This page is a guide to the first hours and days after damage or a theft at Tell your adjuster first, and ask for a claims supervisor to review the file if
your home. It is a summary only. It is not part of the insurance contract that does not settle it. Your agent can help. If we still disagree about the
and it does not add to or change your coverage. The policy form and its amount of a loss, the Appraisal condition in Section I of the policy form
endorsements say what is covered. describes how either of us can have the amount set by appraisers.
To report a claim Contact BEFORE ANYTHING HAPPENS
A few minutes now make a claim much easier later. Walk through your
Claims, 24 hours a day (800) 555-0142 home with a camera and record each room, the closets and the garage, and
keep the pictures somewhere outside the house. Keep the receipts for
Online harborline.example/claims
larger purchases. Find the main water valve and the breaker panel and
Your agent, Denise Trumbull (614) 555-0148 make sure everyone in the household knows where they are. Keep your
policy number and our claims number where you can get at them when
you are away from home.
FIRST, MAKE THINGS SAFE
Get everyone out of danger. Call 911 for a fire, a break-in or an injury. If
you smell gas, leave the house and call the gas company from outside. Do
not go back into a damaged building until the fire department or the utility
says it is safe. If a pipe or an appliance is leaking, shut off the water at the
main valve, and switch off the electricity to wet areas at the breaker panel
if you can reach it safely.
STOP THE DAMAGE FROM GETTING WORSE
Your policy asks you to protect the property from further damage, and it
pays the reasonable cost of doing so. Cover broken windows and other
openings with boards, plastic sheeting or a tarp. Move undamaged
belongings to a dry room. Mop up or pump out standing water and run
fans. Make temporary repairs only, and do not start permanent repairs
until an adjuster has seen the damage or has told you to go ahead. Keep
every receipt.
REPORT IT
Call us or your agent as soon as you can. Have your policy number ready,
with the date and time of the loss, what happened, and a phone number
where we can reach you. Report a theft or vandalism to the police and ask
for the report number. If bank cards or checks were taken, tell the card
issuers and the bank at once.
KEEP THE EVIDENCE
Take photographs or video of the damage before you move or clean
anything. Do not throw damaged items away until the adjuster has seen
them, unless they are a health hazard, and photograph those before they
go. Start a list of what was damaged or taken, with a description of each
item, about when and where you got it, and what it cost. Gather receipts,
statements, manuals and photographs that support the list.
IF YOU CANNOT STAY IN YOUR HOME
Keep the receipts for a hotel, meals, laundry and other extra costs. Loss of
use coverage pays the increase over your normal living costs, not the
whole of them.
WHAT HAPPENS NEXT
An adjuster will call you, usually within one business day, will arrange to
inspect the damage, and will explain the coverage and the deductible that
apply. A separate deductible applies to wind and hail damage. We may ask
you for a signed, sworn proof of loss. If we do, it is due within 60 days
after we ask for it. When a mortgagee is named on the policy, a payment
for damage to the building is usually made out to you and the mortgagee
together.
You choose who repairs your home. Be careful with contractors who
come to the door after a storm, who want full payment before any work is
done, or who ask you to sign your insurance claim over to them. Ask for a
written estimate and proof of insurance before you sign anything.
Comments
0
Comments are added in the local viewer; this copy is read-only.
Values from records
5render unknown
The record values this file is made from: the ones its text names with {{record.field}}, and the fields its template reads. A value here is in the file's source; whether it is readable depends on the look.
| Value | Now |
|---|---|
| home-policy.policy_number | HO-7719024-06 |
| home-policy.expiration | 2027-08-06 |
| mortgage-house.account_number | 0047-338-21965 |
| home-policy.annual_premium | 1637 |
| home-policy.deductible | 1000 |
The values at render time were not recorded: the file was rendered before files/rendered.json existed. Rendering it again records them.